








When structuring earnout agreements for business exits, entrepreneurs should tie payments to top-line revenue rather than profit metrics to prevent manipulation, and ensure the earnout structure provides continuous incentives without a ceiling to motivate continued growth and protect the seller's interests during the transition period.
Earnout Structure: How to Avoid Getting Burned in a Business Sale
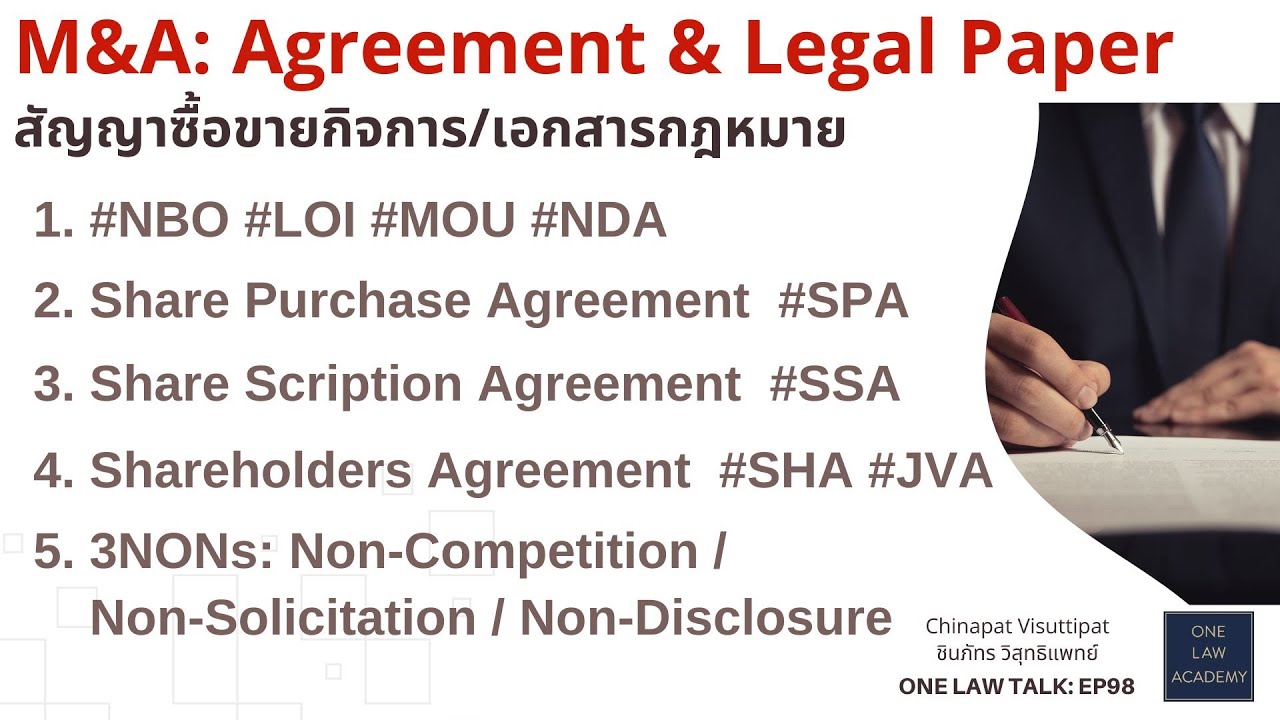
Added:Basic Mergers and Acquisitions (M&A) Deal Structure: Understanding how a standard business acquisition is initiated, negotiated, and closed.
Business Valuation Fundamentals: Familiarity with how companies are valued, including multiples of EBITDA, revenue-based valuations, and asset valuation.
Financial Statement Analysis: Ability to distinguish between top-line revenue and bottom-line net income, as well as understanding cash flow metrics.
Principal-Agent Problem in Corporate Finance: The theoretical conflict of interest between business buyers and sellers regarding risk and future performance.
Legal Drafting of M&A Agreements: Translating negotiated earnout terms into enforceable legal covenants, including dispute resolution clauses.
Post-Merger Integration (PMI) Strategy: Managing operational transitions, cultural alignment, and employee retention after a transaction is finalized.
Tax Implications of M&A Transactions: Analyzing how different earnout payments are treated for tax purposes (e.g., capital gains versus ordinary income).
Alternative Transaction Structuring: Comparing earnouts against seller notes, rollover equity, and licensing agreements as risk-mitigation tools.
335 views4likes51:36Original Release: 2019-07-16
And this was about as bizarre and as easy as it gets.
So, the number for me was a number that would allow me to never have to work again.
I feel like we got top top top.
I went from a sale of, you know, $500,000 to in debt $192 million. This This is Built to Sell Radio with your host, John Warrillow. This episode of Built to Sell Radio was brought to you by PreScore. What on earth is a PreScore? Pre stands for personal readiness to exit your company. And here we're looking to evaluate how personally ready you are to leave your company. You know, when you go to sell a business to have a successful exit and look back on it without regret, you need two things.
Number one, a company that is attractive to an acquirer, to a company that's built to sell. And number two, you personally need to be ready to exit that business. We found that there are four drivers of a happy and lucrative exit, four ways you can personally ready yourself to exit your business. And by completing your PreScore, you are going to see how you're performing against those four major drivers of a happy and lucrative exit. Just go to prescore.com.
Except you're going to hear from a woman named Kristin Dellwo, who sold a company called Stacks. So, Stacks was in the library game. It was a software business, which she sold to one of the largest actually privately held companies in the world, EBSCO, which I had never heard of, admittedly, but it's apparently a massive company with lots of interesting ties and businesses.
What I want you to listen for in this episode is how Kristin thought through a win-win solution for her and EBSCO. So, in part it involved an earnout. Now, for a lot of entrepreneurs, an earnout is the enemy, right? You want to do everything you can to avoid it. But, for Kristen, admittedly, they were early on in the product life, just a million dollars annual recurring revenue, and so they wanted to reach scale quickly, and they figured that an earnout was the best way to do it. She made some really important uh you know, de-risking decisions, which I'll let her explain.
Uh she made one fundamental decision, which I think will set herself up for success when she comes to ultimately calculate the value of her earnout. Um lots of really interesting tidbits and facts here for structuring your earnout.
Here is Kristen Dellwo.
Kristen Dellwo, welcome to Built to Sell Radio.
Thank you.
YOU'RE MY FIRST LIBRARIAN.
ARE YOU REALLY A LIBRARIAN? That's just That's just marketing PR, right? You're not really a librarian.
No, I was a systems librarian for a large consortia. We had about 150 public libraries and 100 school libraries that I was responsible for all their software and network stuff.
Wow. Okay, so you really are a librarian. How did you get into this business, cuz you took an interesting route to get into the Stacks company.
How did you get there?
Sure. So, I had um I was a customer of my co-founder, actually, and I um decided to join forces with him when I kind of reached a ceiling of all the really cool things we could build um with me as a customer. Anything I could invent, they could create, and that was um incredibly powerful. So, I joined the company, and about eight months in, um decided to buy half of that founding firm, and then we uh spun Stacks out of that.
Got it. So, when you say you were a customer, you were respo- I I was joking earlier that you were a librarian, but you were working as a systems librarian.
That's right.
So, we built web and mobile applications um for all of those libraries, and helped administer those and deliver those to those librarians for them to execute.
Um, and that company was my vendor.
Right. And the vendor was a custom consulting company, right? They didn't have a prop off the shelf product. They were doing sort of they'd write a proposal, they'd send you, you know, that kind of stuff.
Yeah.
And what was the name of that company?
Hybrid Forge.
Hybrid Forge. So, Hybrid Forge, for our listeners who are not software guys or gals, they would think of Hybrid Forge as really a service company, right? They would and for tens of thousands Absolutely. So, we bid on, um, RFPs and proposals for custom web or mobile development work. Um, done lots in libraries, health care, quasi government type engagements.
Um, but all very custom projects, very one-off.
And so, you bought half of that. How did you come up with a valuation for that business to figure out what half of it was worth?
Well, you know, I joined the company as VP, um, of business development at first, wanting to focus on sales. It was something I'd always been on the management side and I never really focused on sales. And because we were generating so much library traffic based on the things that we were building and I was going to conferences and telling these stories and showing off these amazing, um, solutions. And so, it made sense to join as sales, but it only took about eight eight months to realize that there were two co-founders, um, of that original firm founded in 2006. And it didn't take us very long to realize, um, that we needed to change direction if we wanted to grow bigger. We were really at this cusp where we were maximizing profit margin and we knew we needed to do something product focused if we wanted to grow.
Um, and so, it really came down to what did we need for the other founder to move on into other things. And he's actually, um, working at the machine learning institute at our local university now. So, he's moved on to some pretty neat things as well.
You confused me cuz maybe you intentionally dodged that question or maybe you But how How come up with a valuation for it? Like it when you said, "Okay, I bought into it." Like, Mhm.
how did you figure out how much Well, you know how co-founders are. You got a shotgun clause on what that looks like. So, it was really about negotiating the price with the founder who was leaving, um more so than the founder who stayed.
So, the the founder who was le- you were essentially buying his shares. Is that right?
Yeah.
Where did you come up with the money to buy it?
Oh, begged, borrowed, and stole. Um there was friends and family money in there. Um we did some creative accounting in-house here. We made some payments over a period of time. Um certainly wasn't something that was in um in my my bag of tricks at that point. Um but it was a pretty exciting opportunity, and so when you're that motivated, you find a way.
So, for folks who don't know a shotgun, you essentially how does it you bought his sh- you basically made an offer for his shares.
Essentially, the other co-founder buys him out, and then I bought those shares.
Um however, the co-founder that stayed helped me make that purchase because that was a business decision that was strategically valuable for him. Um so, he helped make that work as well.
Yeah. Yeah, that makes sense.
So, just so we're clear on the shotgun clause for folks listening you may not have heard, as I understand it, essentially one partner would say, "Look, I'm going to make an offer to buy your shares for X amount of money." And that other partner has a choice of whether to accept that offer or basically make the same offer to the the person making the offer has to agree to accept the same offer they have made.
That's good.
As I understand it. Got it. Okay, so you find yourself the half owner of this company called Hybrid Forge, which is doing custom work and doing a lot of work with librarians. How did the the business of Stacks kind of evolve out of that?
Well, coming into this, we were at that point doing about 60% library work, even though it was very custom. And there was an obvious pattern of creating very similar solutions for each of these customers. And we knew when I was coming in that there was a gap in the market.
You know, it didn't have to be that hard. Coming from my experience being the the consumer, shouldn't have to be that hard to get to where we need to be.
But we did evaluate various SaaS opportunities from within the portfolio.
So we looked at some health care solutions and and some insurance solutions and tried to evaluate what's our best opportunity. But for sure, we're in Alberta, so we're in an oil economy and it ebbs and it flows and it comes and it goes. And when a government changes, it would often impact our government contracts and that work flow coming in and out.
So we knew we wanted to go global. We knew we wanted a SaaS product. We wanted that recurring revenue model. And so we evaluated several opportunities in the portfolio and ended up coming back to Stack's as much I think because of the expertise as well as the relationships, but also there was just a clear market need, a demand.
You know, I think a lot of people would love to get inside your head you and your co-founders head at that at that time.
Um because one presumably option you could have chosen at that fork in the road was to say, "Hey, we've got this profitable little consultancy.
Uh you know, we make good margins.
Mhm.
Sure, it ebbs and flows, but it's profitable.
You I guess there's a a school of thought to say, you know, don't change that. Just suck the profits out every year and live high on the hog and and and and the and then the the the allure of the SaaS product that seems to have caught your fancy was I guess the other option. Now you chose door number two.
Did you guys contemplate the other?
Well, we you can't have your eat cake and eat it too. Um, we still sustained some of that hybrid business and that hybrid work. We still do some of that today, um, even post acquisition. And we largely use that engine to bootstrap stocks. So, rather than being in a position, um, where you're solely dependent on external investors to get where you're going, that gave us a very, um, stable opportunity to invest in ourselves, um, and take our time to build those relationships and be strategic. Um, but we still do some of that work now.
So, you used resources, cash, and development time from All of it. Yeah.
consultancy. So, this is fascinating because I I've I've heard of companies trying this and falling flat on their face because the the the product, in your case Stacks, um, always was second fiddle to the the screaming customer who needed it tomorrow. How did you guys manage to get Stacks out the door with customers always competing for resources?
I think that's really about building team loyalty and and commitment. So, it can't just be the founders who have that passion and that energy and that belief in what that product is. So, um, we incentivized our team early on. We gave away, um, shares to key contributors, but we also opened up rounds every year, um, for employees to buy in and to be personally invested. So, what happened is we've got a dozen folks in here who are as passionate and excited about that product as we are as founders.
So, you Sorry to interrupt, but you enabled them to Sorry about my job. You enabled them to uh you gave them stock and you also enabled them to buy. Were they buying into uh uh Hybrid Forge, the company that had this product that they were working on called Stacks, or were they buying into Stacks as a separate entity?
Stacks.
Just Stacks.
Stacks. Okay. So, describe, if you would, we keep referring to Stacks, but I feel like we haven't actually defined what is Stacks do? What is the product?
What is the software do?
Sure. So, Stacks is a content management system designed specifically for libraries as we market it, but really research-centric organizations. So, we have customers in all information verticals. So, medical institutions, corporations, law firms, academic libraries, public libraries, school libraries. Um so, really started in libraries, but any research-centric organization can benefit from the tailored approach to a content management system that really just knows their business and their core business tools and can plug into them quite easily.
So, let's assume I'm a 12-year-old. I don't know what a content management system is. I know what Google is and I don't really see why you'd need anything more than Google. So, why do you need a content management system?
Well, content management system allows you to build a website.
That's important. What we do is we take EBSCO's products and other vendor products and integrate them so that you get that curated Google-like experience in a website that you've curated. So, not only do you search, but you can also browse and interact with different resources.
And you're browsing your own content or external content?
It's most often a combination of subscribed content, so content they pay subscription to have access to, whether that's academic journals, patents, product launch databases, things like that.
Um subscribed resources, their own resources, resources that they create in-house, um as well as open resources. So, we allow the information managers of the librarians to curate that experience and then brand it all their own.
Got it. So, you're pouring money from the high-margin, but ultimately not terribly scalable consultancy into the creation of this product called Stacks.
As you look back now with hindsight being 20/20, do you think there were one or two sort of seminal points in the development of Stack's that that enabled you to win that that kind of key forks in the road or major decisions that you made that that it ended up being the right ones in hindsight?
I think there were more meaningful engagements rather than meaningful development and I say that because often those pivotal um pieces of the product came from engagement first and we developed them on the heels of a great conversation. So I mean fake it till you make it, right?
What do you mean by engagement?
I think there was definitely some interactions with um key stakeholders or other vendors in the space or customers. Um Caltech was certainly pivotal for us. That was the first customer that we engaged and um as as a product company. So we had done a custom um version of Stack's, an early version that was a custom development with Microsoft's library and we'd done a few that were measurable and and made us known. Um but Caltech was the first product subscriber and that was definitely a pivotal relationship.
And it sounds like there it it as opposed to a hard line in the sand, there's somewhat of an arbitrary line, tell me if I'm wrong, between Hybrid Forge, which is custom consulting, and Stack's, which sounds like a product because it doesn't sound like Stack's is off-the-shelf. You've got to integrate it with an existing Well, that first statement or no?
Stack's is designed to be off-the-shelf in that you can configure it yourself and there are lots of self-guided tutorials and really it's not any harder to work with than a Squarespace or something like that. Um it just knows their business. So it knows you want to put book covers in a carousel. A normal Squarespace wouldn't know that. Um so it's very plug and play and designed to be very self-usable. Um we do have a Stack's line of professional services that is a little more measured and calculated in that we will do integrations that leverage a stack's defined predefined architecture. So, it's not totally custom, but you could come and say I've got this data repository that I want to integrate and we'd say, "Okay, well, it fits in this architecture, this one, or this one."
And these are the fixed prices for that.
Whereas, Hybrid's work tends to look a little more like milestone billing and benchmarks in those kinds of cases.
What was it about creating your own product that was attractive?
Well, I think buying into the company originally for me, I'd always hit like a 2-3 year ceiling on a job, on a particular role, and then feel the need to do more, the need to expand that. Um, so, coming into the company for me, it was really about being able to make it my own and make it a challenge year over year, um, and pivot as I see fit. Um, I think the market opportunity for stacks has been pretty motivating to see the same needs across the world. And because we have relationships with vendors like EBSCO who already have that market share and those relationships, we did have exposure to that global need very early on, which I think a lot of founders don't necessarily get to see.
Is there a personal financial motivation where you know, you borrow, you said you kind of borrowed and begged and you know, to pull together the money to buy into the company?
Is there also that personal motivation to say, "I want to make a return on that money. I've taken a big risk here financially. This is not sweat equity.
I've actually put in money of my own."
Um, there certainly is. I think Hybrid was a successful enough company that we've always done quite well. So, um, not starving artists exactly in the startup space. I mean, we've always had that foothold and had some consistency, so a little less scary. Um, I always think you need something other than money to motivate you alongside. And for me, it was really the impact factor. I mean, when you start to impact research in a big scale and some of our corporate customers are testaments to that, but when you start to influence food production and drug production and the research that goes into these things, you just make the world a better place.
So, I like to lean on on the cleaner water, healthier food, safer airplane impact factor and I I find the less I chase the dollars, the more of them I get.
And how did That's a good point. How did um how did you educate or or did you your staff on that point? Because it sounds like all of your employees on Stack were financially motivated. They were shareholders, uh option holders. Um You just got to work the hardest, man.
You just as a leader Yeah, but did you talk to them about not necessarily chasing the financial gain, but the larger purpose or Uh we talk about the larger purpose because that's what gets me real excited. So, when we get a new customer, a new opportunity and it it nets something positive like that, I mean, I I tend to bring that back as a librarian. I mean, I believe in sharing the knowledge and so I can get pretty excited, but I think everybody's motivated by something different and and certainly the motivators across the team are not the same for everybody.
Um but I think working harder and being a believer, it's pretty hard to watch me sweat it out and not believe that I believe at very least.
Yeah, yeah. Yeah.
But I you know, I at the it's funny with with visions and stuff like that cuz ever since Jim Collins wrote whatever it was Built to Last, Good to Great, I can't remember which one it was, where he kind of revealed for the first time the importance of having a vision and blah blah.
I've been you know, admittedly, I personally been a a little bit skeptical on that stuff. I I think it has a purpose, but it if executed clumsily, um it can sound kind of trite and and fake, right? So, like if everybody's mission, like if you if you distill everybody's mission down, it's basically to make the world a better place. Like if you Google's is to like, you know, organize the world's information. Well, like why is that important? Well, ultimately it's to make it the world a better place, right? Uh, here at Value Builder, we're you know, our goal is to level the playing field for business owners as they approach their exit. Well, why is that important? Well, ultimately it's to make the world a better place. So, how do you find, I guess my question, an authentic vision that is both motivating for your employees, but at the same time kind of believable and real I don't want to say realistic cuz I'm not suggesting it's not realistic, but believable and and that they can kind of I think it's evolved over time. Like if I think back to gaining the buy-in and folks getting excited. And certainly every employee that's walked through these doors has not been a believer.
Um, but I think it's about engagement and about spending time with those folks and allowing them to spend time with customers. So, we've actually over the years as we go to conference and we engage prospects in the market and partners and try to expose them to the industry cuz I'm the only one comes from the library space. I mean, we're a bunch of technologists here. Um, but socializing them and taking developers to a sales conference and allowing them to participate in vendor booths and see the customer engagement and the response. I think it's certainly much more valuable coming from the outside in than it is from me um, going out. But we're also a very open concept office space. So, we're very transparent in what that feedback looks like, good, bad, or ugly. Um, and engaging the team and letting them have that exposure.
Great. Great. Okay, so let's jump forward. So, at some point along the road, you meet this company with this weird name called EBSCO.
Yes.
Nobody will have ever heard of even though they're apparently giant. I should say nobody. I've never heard of them. What on earth does EBSCO do? What does EBSCO actually stand for?
So, EBSCO stands for the Elton B.
Stephens Company, who is the original founder.
That's a guy who needs some branding help. But anyways, EBSCO, yes.
Right. So, um privately held company in the US, one of the largest, I understand.
Um and and so that's grandpa, that's granddaddy there. Um and and that's the legacy. They essentially provide um scholarly subscription content, mostly, um to information organizations around the world. So, I was a customer of theirs in the library space. If you went to post-secondary and you have to cite a research paper, there's a really good chance that that paper is coming from EBSCO.
Okay.
They have exclusive right to a lot of content. They publish a fair amount of content in-house. And now they're starting to index open content alongside that subscription content. Um and it's really their index technology that sets them apart. So, while they have a stronghold on the content side, it's really about how they aggregate that index that in a meaningful way. Um that goes beyond um what Google does in context, um looking at research and aggregating that data.
And and so, how did you first come to work with EBSCO on the Stacks product?
Oh, sure. So, I was a customer of theirs for years. As Chad and I built custom solutions, and then I brought opportunities and relationships um to my co-founder Chad. Um as I brought business his way and he started to interact with the library space, that's when he met EBSCO as a vendor. Um so, at that point now I'm a customer of both these guys.
Um but when we were ready to take Stacks to market, in theory, so not necessarily a turnkey product yet, but really to test the water and see um how how the market's going to respond to that, um EBSCO was one of the first to pick up on that. So, there There some early um discussions around more marketing content than product content.
Okay, because they they had all of the customers that you wanted as customers already.
Right. Right.
Nice. Okay. All these libraries and yeah, okay.
Got it. So you thought, "Okay, we'll partner with EBSCO and we'll allow them to take the Stacks product to their customers and see how it works."
Yeah, and that was a tough decision. It probably slowed us down about a year to go to market because we essentially had to do due diligence as if we were being acquired to be a partner for them to be a reseller or seller of our product. The advantage there though was that we got to build the business model and the price model based on a relationship.
So we weren't trying to shoehorn that in after. So it slowed down our time to market, but I realized very early on that there was no way I was going to build a sales force that had the global reach that EBSCO and those trusted relationships exist.
And so I thought it wise despite all the temptations to just start taking it to market and pedal it to invest the time in that relationship.
And so that first customer Caltech was signed by EBSCO.
Interesting. Chris, go back. So why did you think it would be impossible or not favorable to to build your own sales force? You mentioned I realized early it wouldn't be possible. Like why not?
Well, I think you need to know what you're good at. And I think the biggest mistake I see as I'm, you know, coaching and mentoring and talking to these companies is that you want to be everybody all the time. And nobody's really good at anything. And if you're really good at product incubation as a small firm, there's a pretty good chance you're not that good at sales. Even if you win the sales you have, you don't have relationships. I mean EBSCO has product in 170 countries, employees in 100 countries. I don't have I don't going to on the ground in the Middle East. There's no way. Like that's just not attainable in the short run.
Um and they were a trusted vendor. Every you know, all the entire market. Um I bet you they've got 90% of the market buy something from them.
So there's a lot of entrepreneurs out there listening to this and saying, "Yep, that's what I believed about the big distributor in my industry. I did a partnership based on the fact they have offices in 90 countries and 50 million sales and so forth. And then I gave them my product to sell and they sold nothing."
Well, you can't just give it to them.
Ah, yeah. So what what are we doing wrong? So how did you because I mean the downside of doing a distribution deal with a company like EBSCO is you lose control of the selling process, right?
Like you you're basically handing your baby to someone else to sell. How did you ensure that they were successful in selling it, that they did sell it and not the other 50 things in their briefcase?
Well, honestly, in the first couple of years I was on every single sales call as a sales expert, wherever that is in the world, with whatever team that is.
And it takes a lot of investment in people time for that to be effective. I know myself, I spent a lot of time getting to know the low-level account executives that are out there chasing leads all the way to the top of the executive chain. And every layer of those relationships is important and I think we think dealing with the biz dev team um and building that relationship is kind of all we need. Or maybe we need to make friends with product management people. No, everybody in the organization needs to believe and they need to buy in. And so a lot of FaceTime, a lot of travel, a lot of getting on the plane and going to meet these folks. But I'll say those low-level employees just as important to build relationships with as the top. And fast forward to acquisition time, um you know, I have folks point out all the time, "You know more people at EBSCO than we do." Well, maybe. Um because when you take the time it really makes an impact. And and in the early days, a lot of calls where they just learn how to engage the customer, how to position the product, but you really got to take the time to show them.
What about what what sort of legal protections did you put in place? So, first of all, did EBSCO have exclusivity on the stacks product, or were they one of many distributors?
Um we started exclusive in one market only. So, we essentially sold to eight different markets as they as EBSCO would define them.
Um we started off small with one market segment exclusivity.
Um then we moved up. Of course, the exclusivity doesn't cut out ourselves, so we always had the opportunity to go to market ourselves and do some sales um in parallel to EBSCO. Never found the need to action that. Um when we were doing custom solutions for libraries, we did have a reseller agreement um with another vendor that didn't go as well.
So, not to say that the first one was the golden ticket. Um we certainly learned some things that first time about how to package it, how to control the offering in a way that you can scale it and be productive, which is really that menu of stuff I was talking about.
It really has to be product defined um and not open-ended, I think, in order for You could have kind of option one, option two, option three, but you can't have a custom for every Yeah.
Got it. Like what you know, Henry Ford, you can have any color you want as long as it's black.
Right.
Um so So, back to So, EBSCO, you did not have You had exclusivity in one geographic market.
Mhm. One geographic market and one segment. So, we have public libraries in North America only to start. Um and it was pretty much every 6 months we were adding something to that agreement because we were doing well.
And And why what was the protocol like what were So, you you were giving them exclusivity, which presumably had value.
What were you getting in return?
Also exclusivity. So, they agreed not to resell or recommend any other content management system but ours. So, certainly reciprocal on the on the becoming kind of deeper and deeper entwined as as to So, how did things go from this great symbiotic distribution agreement to acquisition?
Well, I think as soon as we started to tap into all markets around the world, it started to look attractive.
It took a little bit to them to EBSCO, I think.
It took a bit for us to warm up to the idea, I think.
But, there's certainly a lot of perks in how quickly you can scale post acquisition. So, it wasn't an overnight decision, for sure.
And we didn't we didn't sell the first time we looked at it, either. So, Who raised the really about flushing out the terms of what would that engagement look like moving forward and does everybody win in that equation?
So, how did it come about? Did Who raised the the the idea of from in the beginning?
EBSCO, and we looked at it and we we didn't make a deal the first go-around.
We came back and did another round.
Essentially, I think since we've been partnered with EBSCO, we've done a round of due diligence every year one form or another to move on to the next level in our relationship.
Right. Right. And so, what was the change that made it more attractive the second time round?
I think that really the attractive part was the the growth path of EBSCO, the company.
So, where they were at a pivot point in shifting and really becoming a software company and it opened some opportunities to do more with the product line than we had before.
And it just was really getting, you know, a lot of traction around the world and so excited to scale stack specific roles globally. So, not just having sales representatives selling the the platform globally, but having the opportunity to put employees in those places and to really grow that. Um, also selfishly a little bit of, you know, Alberta economic development here um, in the diversification. We're working real hard in Alberta um, to get a footprint. And so to have one of EBSCO's national offices and have an EBSCO Canada, um, I think as as born and bred Albertans, all of us um, Chad and myself, um, that's a feel good thing, too. So it was really about timing and opportunity within the organization to take a leadership role um, on a global scale.
Got it. Okay. So how much revenue did you have at that point? What was either size was I'm just kind of getting a sense of what size of company Stack was at the time?
So take hybrid off the table, just the Stacks product line, we were just reaching a million in annual recurring revenue.
In annual recurring revenue, they call it ARR in the subscription uh, world.
Um, how many employees?
15.
15 and all dedicated to Stacks or also a hybrid of?
Some hybrid in there as well. Um, some some of these guys still wear a couple of hats in in how they contribute. Um, but majority Stacks.
Okay. So um, where does it go from there? So did who made the first move? Did did they say what do you want for if we bought your business? How much would it you know, did they ask you to to revise your number? Did they?
Of course How did they How did they What did they say What did they say?
Just like that. What's this look like for you?
What would it take to sell us the whole company?
Absolutely.
How did you respond to that?
Oh, those guys are brazen and they'll just ask. That's okay.
And how did you say How did you respond?
There's more than a number on the table.
I think for Chad and I, especially Chad's been um, in business for himself for a really long time. Um, me not quite as long, but the idea of having a boss can be a daunting thing, right? Like that's a change in life. So it really became about them um, making sure there was a culture fit and an opportunity to continue to grow and in innovate and incubate product and continue to do the things we want to do and live the life we want to live and and they ended up doing a pretty good job of that.
So but how did you specifically answer the question when they looked over the table, they put down their glass of wine and said, "Kristen, what do you want for this company?" How did you respond?
I don't even know if I remember that the full response like right there. I mean, they do ask those questions.
Of course that number is not a simple number, right? You We all We've had this conversation lots amongst our share shareholders of, you know, what's our current minimum? What's our benchmark? But the reality is a good deal with a private company there's a lot of math involved to get to that number, right? Like it's not all you just win the lottery today and that's it. It's a complex sum. I mean, there's lots of numbers and those are percentages and, you know, they come in different values that equate to that number. So certainly not black and white and certainly took a few tries to find a model that worked for everybody and and where everybody felt still incentivized and comfortable.
So I I'm reading between the lines as saying that you did not respond to Ebsco and say, "We need X million dollars or there's no deal." Like did you ever answer in that emphatic way?
No, it was more like, "But I want to be as big as you and I want to contribute to the bigger machine that is Ebsco."
And as a family owned private company, that's a real conversation that you could have.
So it was even more than just stocks itself. It was we want to be a part of this thing that is so grand.
And I think timing mattered about where they were going as a company, but it was really about more than stocks.
So it sounds like you were you were setting yourself up maybe intentionally or not for kind of an earn out type deal where there was there's a uh you know, if things go well, there's a sort of a big Yes.
pot of gold at the end of the rainbow, so to speak, but we've got to make sure that So, again, you may not be able to answer this and I appreciate it, but I've got to ask, what proportion of the deal was cash at closing versus earnout potential? Are you able to share that?
I can't give you an exact portion, but I can tell you a little bit about the structure and that that that purchase price was pretty modest.
Um the earnout is definitely the larger component. Um but I think it's critical it was you know what, a good deal is one where everybody wins and it was important for them to know, I think we would have been too early to exit if we would have done it another way. Um I don't think the product's at the level of maturity. I don't think um we've established our market presence in all our market segments well enough.
I think they really need us to show up.
So, to de-risk the deal for them, it was critical that we are still incentivized and we show up tomorrow. I mean, that's pretty important.
Yeah. And and you know, by the same token from your perspective to to kind of you know, make sure you protect your downside, I'm assuming you needed some cash up front so that if the deal if everything just kind of fell apart for whatever reason, there was you know, you were covered, so to speak.
Certainly. So, I mean, when we looked at how do we de-risk, we started to look at things like maybe it'll be based on revenue and not profit to be sure that that big company isn't going to erode our margin.
It it being the earnout goal.
Right.
We're tied to revenue as opposed to profit. That's one we've heard a lot on Built to Sell Radio over the years.
Uh so many people tie their earnout or the the acquirer wants to tie it to EBITDA of the division and that can be manipulated. And so, you guys were super smart in saying, "No, we're going to tie it to revenue."
Right. I think confidence was high in our relationship. EBSCO has a very similar culture and over the years in working together to get this product off the ground, we certainly got to know each other quite well. So, I think there was low risk in not being successful.
But certainly there were things that both sides needed in order to make it comfortable. I think a contributing factor to the decision to sell early as well comes down to the ability to scale and whether or not it's worth it to spend money fundraising to scale or to just scale via known path that you can scale right now.
And and it our market demand was getting really high. Like we're growing very fast and having a presence all around the world. And so, this a little less red tape, believe it or not, to get to where we're trying to go here in a short turnaround.
So, you were you also courted by investors, venture capitalists, or or private equity?
Yeah.
And so, that was another route that you were considering. What ultimately what was what was not attractive about raising money and and continuing kind of independently?
Well, I think what's unattractive about it is the process of raising money. It's not the funnest thing to do. Going out and doing the pitch. I mean, when you go do the pitch and you close the sale with the top university in whatever country, that's a good feeling. When you go and do the pitch and it's just a different kind of investment deal where someone else is reaching in your pocket, those are tougher things. They don't feel as good. It's also not how we wanted to spend our days. The product is hot. The market opportunity is hot. Do we really want to spend time raising money? I mean, you're a fellow Canadian, you know that's not the easiest thing to take American dollars over here.
And so, it really was about where are we now? What's our fastest path to where we want to be?
And are all those needs met, but, um, certainly not the funnest part of of what we do.
Okay. Okay, so let's go back to the earn out cuz again, reality for virtually everybody listening to this show is there will be some transition required, right? Some period of time where you as the former owner or the the current owner helps the new owner, you know, kind of monetize or or or capitalize on what they purchased, right? One form of that transition is earn out.
Uh, so one of the things you did was tie your earn out to the achievement of a top line revenue goal.
What else did you do to de-risk your earn out?
Oh.
Well, I mean, other than tying it to revenue, um, we do have it tied to all our lines of revenue, so not just the SaaS product. Um, it is tied to to continuing all of our business, um, the way that it is. Um, certainly comes with some nice, um, employment as well. Um, but there is a run there where we need to finish building the business. We're certainly not done that yet and I think, um, it it's pretty, um, secure in looking at scaling this business. I mean, just the transition of support and implementation and all those day-to-day things into the machine as the volume grows, um, there's certainly work to be had there. Um, but they need us to show up.
And and what happens if at some point, God forbid, they fire you?
What what then?
That would be terrible. I know it'll never happen, but what if? Did you I'VE NEVER BEEN FIRED IN MY LIFE. I would be mortified if I got fired. I can't even Let's just say it won't happen. I'm just saying what if it does happen? Is there some sort of clause in there that protects you if they if that were to happen?
Our non-compete isn't too serious and I think the lessons we've learned in this industry likely um if we were to do something again, um it would likely be a similar solution in a different market use case.
So, on the consulting side of the business, we've had the pleasure of working um in healthcare, quasi-government, insurance, operations, um lots of different organizations and built solutions. So, I think there's um certainly with myself and my founder no shortage of ideas and market opportunities. Um but I think we just go again.
Got you. Um what advice would you have? Uh fellow Edmonton entrepreneur comes to you and says, "Kristen, I'm I'm thinking of selling my company to a partner uh that we've worked with for a while.
I know you've done something similar.
What do I What do I need to be aware of?
What do I need to think about? What are What are What are the things that I need to kind of the gotchas that could crop up?"
Well, I think you need to know your numbers. I very rarely talk to a company or or mentor anybody who um knows what their customer acquisition costs are, knows what their annual costs on a customer are. I mean, we tend to talk about margin on sales products. Like, the only spend there is hosting and and development time, and that's, you know, really, really foolish. And so, I think um know your numbers as you go into those exercises because there's a lot of numbers back and forth. Um the due diligence process um is certainly not for the faint of heart. Um and know what kind of life you want to live. Like, know what things matter to you. And it that's often not a dollar, but more lifestyle generated. So, make sure that you think about those things because I certainly did in this equation to say, "This is how I want my day-to-day to look like. This is how I want to live my life." And we got to make sure that that's going to continue for me to be happy in my my life. So, What's What's been the biggest impact on your the way your day-to-day life unfolds now that you're a division of EBSCO versus independent?
Uh well, on the day-to-day in the office, I mean, I may delegate invoicing, but I still have to tell somebody to send the invoice. So um a lot of the functions are delegated into other teams, um but I certainly have a pulse on that and you still you need to engage those folks in order to do that.
Sure.
Um it certainly netted uh a different level of travel. So I said before like, you know, you got to get on the plane and you need the face time. Um that's certainly increased even since acquisition.
Where is EBSCO located? Where are their main offices?
Uh they have the information services is headquartered just north of Boston, the North Shore in Ipswich, Massachusetts.
Um and then EBSCO Industries, the big head office is down in Alabama.
And so are you traveling from Edmonton to those offices?
Yeah, and still doing um events or conferences and and um things like that.
Um but as a startup, you have a good reason not to go uh cuz you can say, you know, I'm being fiscally responsible. Well, now as big part of the big machine, they're a little happy to make those investments to make sure we're in those places. So um I don't have any excuses anymore other than uh I want to see him spend every other week with my kids.
Yeah, yeah, yeah, yeah, yeah. That's interesting, right? Because you do take away that that cost, you know, not cost consideration is not the right words, but there's deeper pockets there, right? So we're asking you to grow the business, go grow it, right? And that means traveling more often. Interesting.
Yeah, and that might not work for everybody.
No, it might not. I mean, I think I could probably get away with less, but I'm pretty motivated to see this succeed and to make it as big as we can be um by design in the structure of the deal. So uh somebody did something right in making sure I was motivated.
So, again, that's Tell us about the structure. So, as much as you can share, it's there's an earn-out component that is tied to you getting top-line revenue.
It's just revenue based. I don't have targets like that.
Okay. And so, it's revenue based and but is it shades of gray versus it's either win or lose or you know, is there a consolation prize, so to speak?
No, not really. It's pretty straight up.
Like it's a pretty black and white deal.
We sell this much, this is how much we get.
So, it's pretty straight up.
As big as we can make it, we can continue to win. So, you know, we tend to to look at things with a bit of a lean business case, which works out okay cuz percentages sound real palatable in a lean business case. And now I think, you know, all parties are just excited to knock it out of the park and see what we can make those numbers look like.
For sure. But I guess for people negotiating a similar deal, I'm trying to get a sense of like if And again, we can maybe take this out of if it's too personal, we can take it out of your specific situation and talk about your friend who is going through something similar.
You know, there's is cuz there's one way to structure an earn-out, which is all or nothing.
Meaning, you know, let's just make a number. If you hit 3 million in revenue by this date, you get this amount of money, right? Kind of one way to do it.
Another way to do it is say, "Okay, you know, our goals are to get somewhere between 2 and 5 million in revenue and obviously there's more for you if you hit five than there would be if you hit two." I guess what I'm asking is is it was more like the second scenario where there there are different sort of performance thresholds and corresponding payments or is it all or nothing?
It It's just straight up. Like the more revenue we do, the more for I make.
Okay. Okay.
Just like that.
Okay.
There's no ceiling.
Okay, got it. Okay, so that's helpful.
held business, right?
Yeah. Yeah. That's helpful. So it is there is no ceiling per se because That's right. There's no minimum either.
Got it. Got it. That's helpful for sure.
So it just really unleashes you to go sell. Now that's your wheelhouse, right?
You I mean you were I mean you shared it earlier that was the the business development piece was what you brought uh to Hybrid Forge. So what about your partner Chad? What's his sort of specialty?
engineer.
So how did he get comfortable with this idea of putting all of his eggs in in top line revenue as as I mean I'm sure he trusts you but at the end of the day it's a big chunk of his wealth and is tied up on I'm sure he still has moments of oh my god, how did I get here? How did this happen? But I think over the years, you know, you build a trust relationship and I always say proof's in the pudding. So as long as every year it it's evolving and and you see the results of those things. I mean I think we've come a long way over the years and certainly we've had ups and downs and all the above along the way but um he's pretty excited, too.
What was the biggest deal point for you and Chad that to work through with with UpSkill? Like what what the deal? What was the biggest point of frustration or sandpaper?
Uh financials I think as a small business, you know, we didn't have to be too rigid on how we booked recurring revenue or how we organized our finances, you know, as as two entrepreneurs in a small company, you can really just kind of treat it like a marital account and everybody knows their boundaries and their swim lanes and you know, you have some respect for the other person and so I think working through the details of the financials and getting everything um where it needed to be for the buyer. I think that was probably, you know, the biggest sweat moments where you're down to the wire and you got deadlines and you got to, you know, produce things in a certain shape and a certain format and um there was some sweat in there. I think strategically or um philosophically, what was the hardest part to to figure out was what our roles would be within EBSCO um and how we would continue to ensure that we had growth opportunity and the opportunity to invent solutions. I mean, that's really what gets the both of us up in the morning. So, we found ways to make sure that we make a good living doing just that. So, ensuring that we didn't lose those creative freedoms, I think that was probably philosophically the biggest challenge was to define roles for ourselves that made good sense.
How did it work out for your employees who also had options or shares and stocks?
Sure. So, we um gave their investment back plus some interest and everybody's part of that earn out.
Uh okay. So, you've been you've been able to tie them to the earn out, but they got the original amount of money that they put in with with How did you figure out the interest rate?
If you're not watching the video, Chris is putting his fingers up in the air to find out which way Stick your finger in the wind.
Yeah, yeah, yeah. Got it. So, it was a bit of a guess. Okay.
Um Did you buy yourself anything uh any trophy to uh to to mark the the win of selling your company to a I actually did. I bought a house. And and I watched as I was on a conference security conference called this morning, I watched a moose take a swim in the lake out of my backyard.
That's really Really.
Wow. That's fantastic. So, there's a lake in your backyard.
That's right.
Oh, good for you. Good for you. So, you must be just outside Edmonton then or Yeah, just east of Sherwood Park.
Oh, there you go. Well, that's fantastic. I'm congratulations on your new home.
Hope the moose got a good drink of water.
Where where where do people find I mean I know people are going to want to reach out and say hi. Is there are you kind of a LinkedIn person? Do you Do you connect with people that way or is it Twitter? What's the best way to people to reach out and LinkedIn's definitely my go-to. I tend to Twitter stops at the conference, I think. I got too much going on. I I I struggle to keep up with the Twitter, but LinkedIn's a safe bet.
So, it's Kristen Delwo, d e l w o.
That's right.
On LinkedIn. And where do people find out about Stacks and EBSCO if they want to learn more about Stacks?
stacksdiscovery.com and ebsco.com.
stacksdiscovery.com or ebscodiscovery.com.
Kristen, thanks for joining us.
Thanks so much. Cheers.
Bye-bye.
Thanks for listening to Built to Sell Radio with John Warrillow. For complete show notes with links to additional resources, visit builttosell.com/blog.
John is the founder of the ValueBuilder System. To find out how to improve the value of your business by 71% visit valuebuildersystem.com.
John is also the author of Built to Sell, Creating a Business That Can Thrive Without You, and The Automatic Customer, Creating a Subscription Business in Any Industry. Connect with John at facebook.com/builttosell or on Twitter at John Warrillow, w a r r i l l o w. Thanks for listening.
Up Next

17:42
Business Valuation & Deal Structure: A Practical Guide
@carlallenofficial
52.6K views•2023-03-17
66:41
Web3 Social Decentralization: Farcaster Co-Founder on Crypto Social Networks
@levychain
1.5K views•2022-10-18

15:23
Decoy Effect: How Pricing Psychology Influences Consumer Spending
@bobinvestsUS
90K views•2026-01-05

17:30
The Planned Obsolescence of Light Bulbs and Tech
@veritasium
25.3M views•2021-03-26
Related Study Plans & Knowledge Roadmaps
Structured learning paths in Business
business
CPG Retail Strategy: Pitching & Trade Spend
01Foundations of the CPG and Grocery Ecosystem
02Retail Math and Designing the Pitch
03Securing Shelf Space & Category Reviews
+ 2 more learning modules
12h5 modules
Explore Roadmap
business
Pop-Up Retail: Strategy, Design & Execution
01Introduction to Pop-Up Retail & Strategic Goal Setting
02Budgeting, Site Selection, and Legal Essentials
03Experiential Retail Design & Visual Merchandising
+ 2 more learning modules
15h5 modules
Explore Roadmap
business
Reg CF: Startup Funding, Marketing & Launch
01Introduction to Equity Crowdfunding & Reg CF
02Platform Selection & Legal Preparation
03Crafting High-Converting Campaign Assets
+ 2 more learning modules
14h5 modules
Explore Roadmap
business
Productized Services: Scaling Solo Freelance
01Foundations of Productized Services
02Packaging and Scope Definition
03Pricing and Subscription Models
+ 2 more learning modules
15h5 modules
Explore Roadmap