














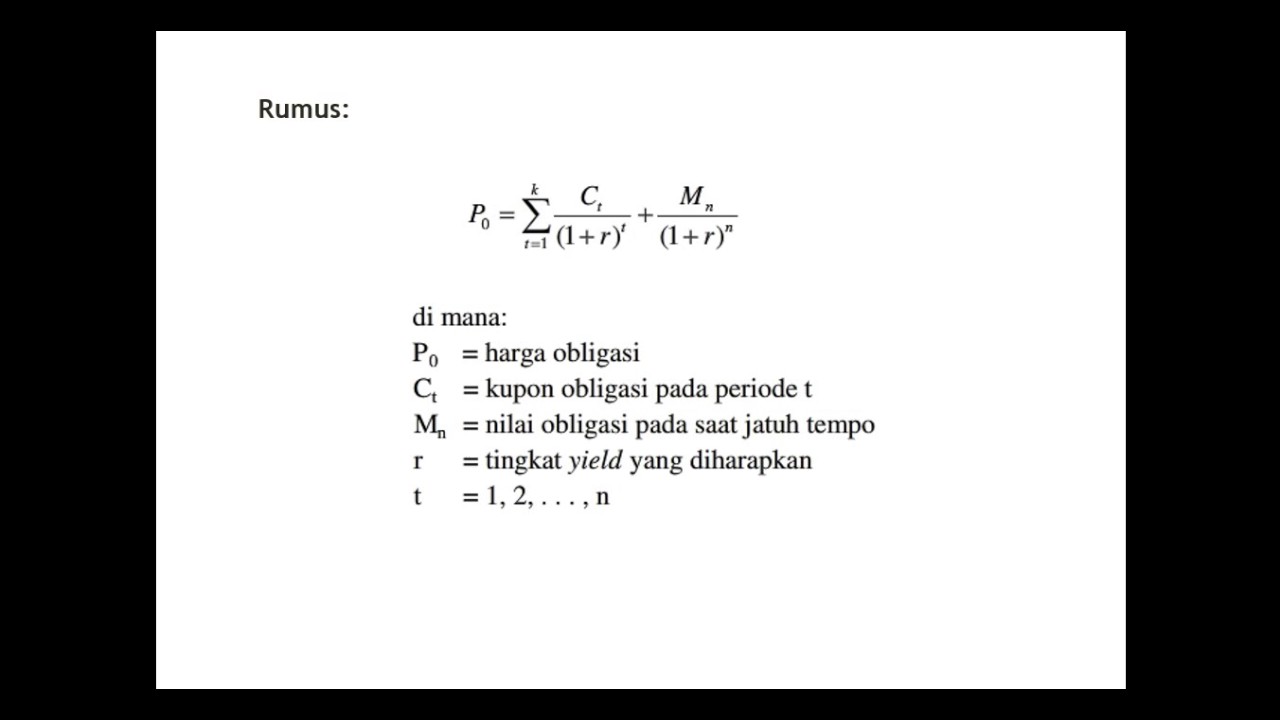
When the Federal Reserve lowers interest rates, winners include variable debt holders (credit cards, Afterpay), home buyers (lower mortgage rates), corporations (cheaper borrowing), and the construction industry (lower construction loan costs), while losers include cash savers (lower interest returns), those with fixed-rate debt (inflationary pressures), and renters (potentially higher housing prices due to increased demand). The Fed's rate cuts aim to stimulate economic growth by encouraging spending and investment, but the effects vary significantly across different economic participants.
Federal Reserve Rate Cuts: Winners, Losers & Economic Impacts
Added:Understanding the role and mandate of the Federal Reserve, including its dual mandate of price stability and maximum employment.
The definition and mechanism of the Federal Funds Rate and how it influences commercial interest rates.
Basic principles of supply and demand in credit markets, specifically how interest rates affect borrowing and saving behavior.
The relationship between inflation, economic growth, and central bank monetary policy (expansionary vs. contractionary policy).
Analyzing historical Federal Reserve rate cut cycles (e.g., 2008, 2020) and their long-term macroeconomic consequences.
The concept of Quantitative Easing (QE) and other unconventional monetary policy tools used when interest rates approach the zero lower bound.
The global economic spillovers of Fed policy, including its effects on currency exchange rates, capital flows, and emerging markets.
Advanced portfolio management and asset allocation strategies to hedge against or capitalize on shifting interest rate environments.
79.9K views1.4Klikes14:44Original Release: 2024-08-12
If the fed starts to lower rates in September, what can we expect?
And more importantly, who will the winners and losers be?
This is a critical topic because I think a lot of people are hanging on these.
Quarter point, quarter point.
It seems like a little bit of a marketing and a political play to me, but we are expecting them to lower rates a quarter of a point in September.
They haven't typically said that, but they've alluded to it either way though.
I for a for all of us said what the fastest rate increases in 25 years.
So we've all just felt the pain.
And thankfully inflation's now at it's about two and a half I think so.
And there is a bit of a lag.
So it's going to continue to come down.
So the quarter point is probably not a bad strategy, but I can't imagine it's going to do much.
Well you have to think though for one I think a big thing that it does is it signals to corporations, hey, don't let go of your people.
It's, you know, don't, don't.
Because, you know, as we'll talk about later, we're starting to see higher jobless numbers.
So don't let go of anyone yet. Don't worry.
We got your back.
We're going to be lowering rates, you know, more continually.
The one thing I always say though, in with investing hope is a bad strategy.
So we get hope.
Like but I do get the quarter point.
I get it like right maybe.
And hopefully it's it's the beginning of a, you know, several well in it's right before the election.
So you can't fail to acknowledge that.
I think, you know, we have to touch on, you know, the unemployment numbers.
it jumped to almost 1.9 million on unemployment, which is the most in the last three years.
Yeah, I saw that is, 2021, I think was the when it got that high.
So essentially what that means is more people get more money on unemployment as a benefit than actually going out and finding a job, because it's hard for them to find jobs right now and they can't find anything to get off of unemployment. That's essentially what it means.
So while it's not everything, it's certainly an indicator.
Well, and also the jobless claims are starting to go up and we're at our 10th, straight week.
It's come in higher than normal. Right.
So what that means is a lot of people are getting laid off.
Maybe they're not on unemployment yet.
They're just considered jobless.
You know, as you're seeing these trends that jobless number is an early indicator that the economy's not doing well.
Yeah.
We're at 4.1 right now as of I guess, the end of June.
So there's about a month lag.
But that's going up.
And so you've got unemployment going up, which believe it or not, the fed kind of wanted they've talked about they've always said low unemployment is inflationary.
So what that actually means I remember when I was like 3.5, 3.7 where actually employers were fighting over employers.
employers were fighting over employees.
And so the the wages were super competitive.
That's good for the employee.
I know it says 2.5, but have you seen groceries go down and you know, well nothing's went down.
But you see that still going up.
Well maybe not going down is maybe it's not going up as fast, but, I'm certainly not seeing a lot of things going down.
Well, I think it's important to note, though, that this is the biggest deal is if they cut a quarter point in September, which we're planning on them doing.
This is a pivot in their strategy.
So they've been holding interest rates higher for longer, and they're essentially accepting a higher than 2%, inflation number before they start cutting.
Well, which we've seen countries all around the world do we just specifically haven't done it. Our. Yeah, we're kind of lost.
If you look at the central banks, we're the last ones to do this, which is fine, but there is a bit of a lag.
So even though we're two and a half, my guess is you're going to potentially see certainly rents are going flat.
You were starting to see softness there.
And that's a big piece of the CPI.
It's like over 40%.
So I do think that you're going to see the inflation rate go down even more from is who are the winners and who are the losers.
As rates get cut.
Yeah absolutely.
And it looks like the fed wants to cut.
You know right now they're still projecting for rate cuts in 2025 and 4 in 2026.
So if they were to do this we want to look at who wins and who loses because there's definite, positives and negatives that somebody's 100 grand that that's not going to that that is not going to happen.
Like there's no way that they can project through 2026 what rate cuts are going to be?
Well, of course, but that's still what they're still it's a it's showing the pivot though that they are wanting to cut rates and they're they're hoping to get I do mind that. Yeah.
What they're saying is if they do five quarter points one in September then for for next year, let's say that's a let's one and a quarter that brings rates down into about 4.25in.
Yeah I guess so.
That would be great.
That would be really good for the economy.
At the same time don't forget what will be going on.
Here's what will be going on.
Commercial mortgages will be fully exposed.
And I've talked about office buildings and apartments and all that stuff.
There's massive disruption in that area.
The Afterpay, that whole piece.
You know, where you're seeing credit card debt really, really, really high.
That will certainly get some relief.
But a lot of people are financing things right now.
They're financing rent, they're financing food, they're financing purchases.
And so that will help a little bit.
But there is a point where people have to pay that back.
Yeah.
So like that's one of the first winners as we were talking about is people holding that variable debt. So you know, like you were saying like with the credit card companies and Afterpay is a big one.
I don't know if you guys know what Afterpay is, but I'm sure you've all witnessed it.
When you go to buy something and they're like, do you want to put this in like 3 or 4 payments or do you want to pay it all at once?
a lot of people have been doing the 3 or 4 payments on many, many things.
So that's starting to stack up.
And what I think you guys need to realize is I have two kids in the 20s.
They're both in their 20s.
And so this is what they're saying to us.
Yeah, kids are using Afterpay.
This is not something that maybe on a lot of your radars, but our sons specifically said that this could be what happened to you guys in zero eight, right?
Yeah.
And a lot of people are taking the retailers are taking advantage of this.
Right. Like I have a friend that works at Michael Kors.
She said, you know, at least 25% of her purchases go on Afterpay, not herself, but from the customers.
You think about that.
That's a huge number.
I wouldn't be surprised, you know, if even your luxury brands are doing this because it's on Afterpay to get the money.
It's not essentially on the brands themselves.
So of course they're going to want to sell to whoever wants to buy it.
However, they buy it.
And we saw a 12% jump in flax, which is the company that finances apartment rent.
So that's what we saw as a company.
So what that means is we get paid from flax and then the residents, if they're qualified, actually pays flax.
So we're starting to see these financings happen all over the place and not just in those two spots.
And I also, you know, think that those people can be winners because that debt can, you know, the interest rate on that debt can go down.
But those people can also be losers because they may want to add on more debt.
You know, if you know the economy that's really what happens.
What happens is when rates go down, people stretch a little bit more.
They get that bigger purchase.
That's unfortunately inflationary.
You know that could be inflationary.
So the winners of lower interest rates are of course, all the things that we just saw when rates were low, not just even a couple of years ago.
Right. Yeah.
So think about electronics.
You think about tech, think about car purchases, think about real estate, all that stuff over a period of time will get a little bit easier.
Hopefully that will incentivize people to be able to buy houses again.
Right.
But of course, depending on where their rates are they may or may not decide to do that.
Yeah.
So although another winner could potentially be home buyers if rates go down.
But we could see an increase in housing prices.
So then that would make them a loser.
So some of this kind of goes either way.
Right. And refinances even. Yeah.
Which would be good for all those commission sales people.
Right.
Both on the loan side and on the realtor, you know, single family site.
Absolutely.
And I think you have to add in, like we were saying, retailers and corporations.
So retailers, if that's cheaper and easier, they're going to have more people buying their stuff.
Just like we saw lines that, you know, Louis Vuitton and all that stuff in 2021.
but then also the corporation.
Yeah.
Because, you know, they have better borrowing and they're able to kind of move that economy along and benefit from them.
I think it's important that you guys really understand a lot of businesses.
I would say a lot use lines of credit for stuff.
So they are borrowing at low rates from their bank based on, you know, whatever they got as collateral.
And as the rates go down, it actually helps them too.
So in other words, the corporations potentially can stretch as well, which can also help boost economy.
And Construction's a big one.
That's going to be a winner too, because obviously construction loan is not fixed.
So in these high rate environments, it's hard to want to build anything because nothing is fixed for you, where if things start to go down, construction loans might start to reemerge because they're like, okay, rates are going down, they're not going up.
So let's go ahead and start building.
And just to put that in perspective, as somebody who's building when we started building a project two years ago, our rates were in the 4 to 5% and now they're over nine.
So just by having that come down, let's say a point in a quarter is significant.
If it get into the sevens, it saves us a lot of money each month because a lot of interest rates are floating and they float with some other kind of indicator like the ten year Treasury. As an example, let's talk about some losers because we talked about the winner.
So one of the losers, they're going to be people that are sitting in cash.
Or if you are a saver that's a good point.
Yeah I mean I know I, I was with a buddy last week and he's got a ton of money and cash is sitting in these 5% treasuries, you know, and he's cashing in right now because if he can make 5% on cash secured by the government, why wouldn't you just keep it there?
And same thing with savings rates.
I know a lot of you hopefully moved your money from checking in to, let's say, a money market and you should be getting you should be getting north of 4%.
If you weren't, then you missed that window.
But as rates go down, those interest rates on cash is also going to go down.
The savings rates will go down.
Yeah.
And also home buyers can be losers too.
So for those of you, you know, looking to buy a home, prices potentially could go up when rates go down.
That's what we think would happen.
Unless there's an abundance of supply that comes to the market, that would be the only thing that could change that.
It would be a bit of a mixed bag there, but you're right.
I mean, you hold, you're going to have some refinancings, you're going to have some new home purchases, you're certainly going to have some new construction, but it's all going to depend on how quick and how how quickly is that going to be actually delivered and then that the supply itself.
So the more supply, the better the price for the consumer.
Yeah.
And then you have to look at inflation too, because all of these you know, rate cuts are probably going to create more inflation.
So that's really hard on anybody on fixed rate debt.
That's really hard on anyone that maybe is on a salary and in a job that's not, you know, in super high demand, you know, inflation, if inflation has been infecting you in a negative way over the last few years, it probably could continue to do so if they start cutting rates.
Yeah.
And so that's why you're going to see a quarter point in a quarter point a quarter point.
You're not going to see these.50.75 interest rate increases like we saw.
It's not going to it's not going to go down like it went up.
So it's going to be slow and methodical and over a long period of time.
And this last one the renters this is an interesting one.
We were kind of debating on this because, you know, is it are they going to be a winner.
Are they going to be a loser.
It just really it's interesting.
There's a couple theories of thought on here.
So if construction is cheaper and easier and a winner, that could add supply to the market, what would be good for it would be good.
You know right now you guys probably know.
In fact, we're starting to see that some construction projects that we started just 2 or 3 years ago, we're renting up.
So in other words, there's a big lag with apartments and you might break ground on something in 2022.
It might not be delivered to 2024.
It's just could take that long.
And so those units are now hitting the market.
We're starting to see people that would normally buy a home now renting.
These are classy, beautiful apartments.
But we're seeing a much better renter that would typically be buying a home.
And so that could reverse because I think generally people would want to buy a home versus renting an apartment.
It's not always a lifestyle choice.
Sometimes it's just I'm going to wait and see where the rates are going to go, because the mortgage payment is so much higher than the rent, it just makes more sense for me to rent in this area.
You know, maybe it's temporary, maybe it's long term.
But I think a lot of people are going to be sitting on the sidelines right now as a result of that.
And if rates go down to your point, there will be more units delivered and the affordability all of a sudden becomes better for the person that's buying the home.
Now, one thing that could change all that is, you know, Biden just proposed national rent control.
I saw that, now this is a longshot to to pass with rent control.
You would not get new supply, which would then potentially make the renter the loser unless you were locked into a lower rate.
But look at it the other side of it.
Like if there is rent control, then you're going to have there'll be less investment in that area, and most people will probably back off from that and rents will probably go up.
Yeah. I mean that's what happens.
I mean, your most expensive zip codes have rent control.
Yeah. Right. And they've tried it before.
We do need something to help the renter.
But rent control clearly does not work because as we all know, money goes where it's treated best.
And it does not go to rent control markets.
Right? Yep. Absolutely. Thanks for joining us.
And make sure you click on our next video that we did.
And it explains how owning a house before 2020 and after the differences in that.
So you guys.
Up Next
13:45
Quantitative Easing and Inequality: A BBC Interview Analysis
@garyseconomics
32.8K views•2022-01-26
5:07
Impact of Yuan in Indo-Russian Trade Amid Sanctions
@WION
261.9K views•2022-07-01

40:17
Housing Affordability vs. Investment: The Economic Paradox
@KenMcElroy
36.8K views•2024-09-23

113:18
The Age of Easy Money: Fed & Inflation | Full Documentary
@frontline
21.2M views•2023-03-15
Related Study Plans & Knowledge Roadmaps
Structured learning paths in Economics
economics
Sovereign Debt: Defaults, IMF & Restructuring
01Introduction to Sovereign Debt & Government Bonds
02Debt Sustainability & Credit Ratings
03Anatomy and History of Debt Crises
+ 2 more learning modules
12h5 modules
Explore Roadmap
economics
Market Design: Matching Theory & Gale-Shapley
01Introduction to Market Design and Price-Free Markets
02Two-Sided Matching & The Gale-Shapley Algorithm
03School Choice Systems and Mechanism Design
+ 2 more learning modules
10h5 modules
Explore Roadmap
economics
Impossible Trinity: Forex, Capital & Policy
01Introduction to Monetary Policy and Central Banking
02Exchange Rates and International Capital Flows
03The Mundell-Fleming Model
+ 2 more learning modules
8h5 modules
Explore Roadmap
economics
Healthcare Economics: Market Failures & Systems
01Introduction to Healthcare Markets and Market Failure
02Asymmetric Information and Adverse Selection
03Moral Hazard and Insurance Design
+ 2 more learning modules
12h5 modules
Explore Roadmap