








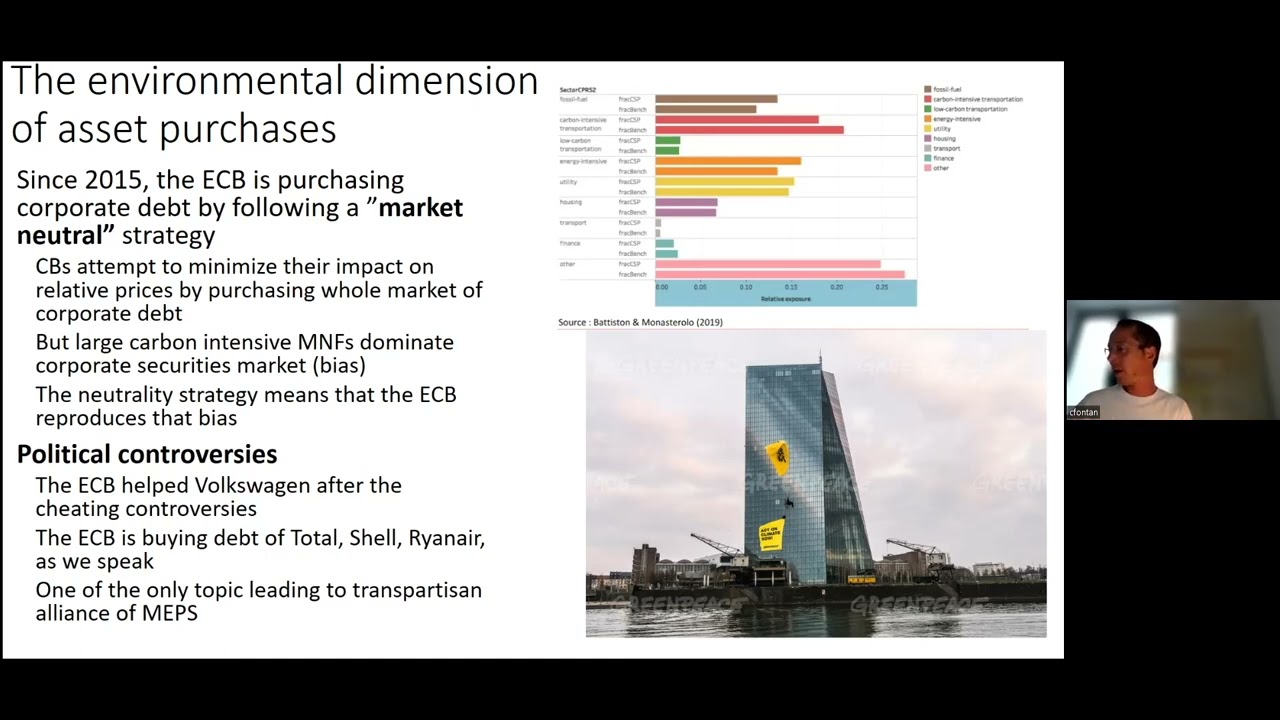




Central banks regulate money creation, a fundamental state power that shapes society, yet their independence from democratic oversight creates democratic problems; while central banks are technically accountable to legislatures, this backward-looking accountability fails to give elected officials meaningful power over monetary policy, leading to a cycle where delegation erodes democratic participation and creates technocratic governance that undermines democratic legitimacy.
Central Bank Independence and Democracy: A Political Theory Analysis
Added:The basic mechanisms of monetary policy, including interest rates, money supply, and inflation targeting.
The foundational economic theory behind Central Bank Independence (CBI) and why insulation from political cycles is traditionally favored.
The principles of democratic accountability and representative government, particularly how policy decisions are expected to be responsive to voter preferences.
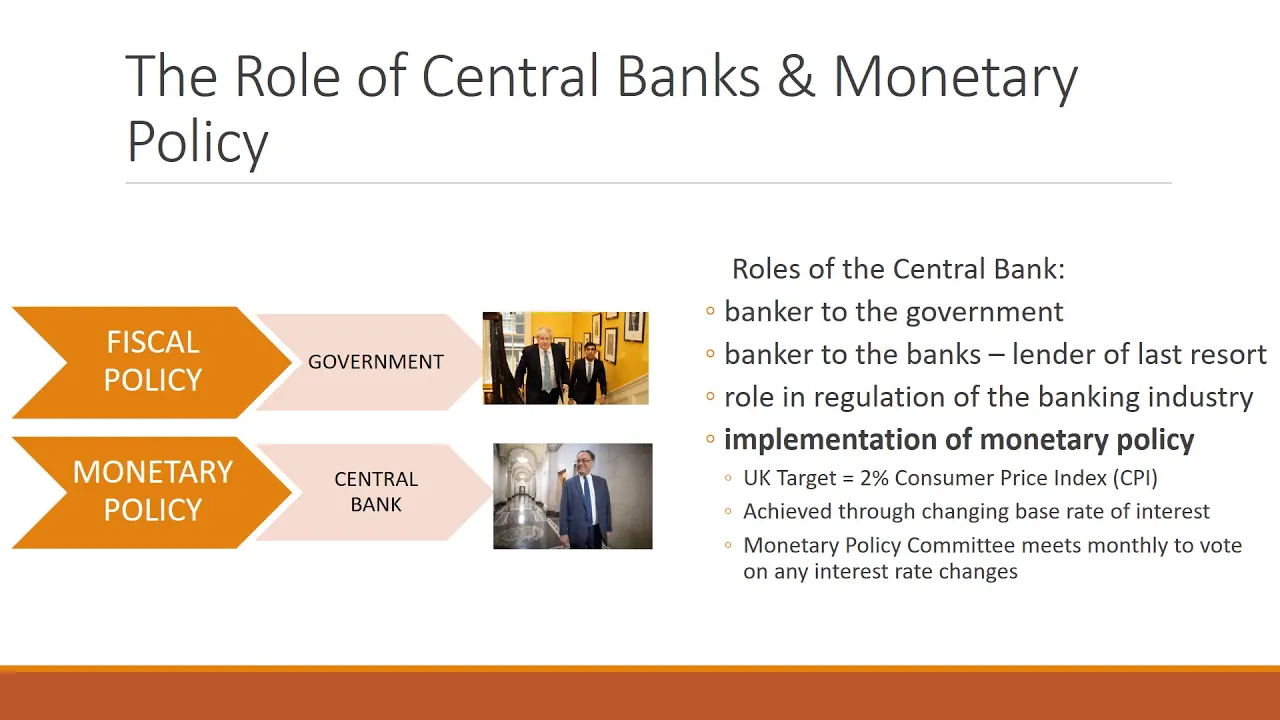
The distinction between monetary policy (managed by technocratic central banks) and fiscal policy (managed by elected legislative bodies).
The distributional consequences of monetary policy, exploring how central bank decisions (like quantitative easing) impact wealth and income inequality.
Alternative frameworks for central bank governance, such as green central banking, public banking, or democratization proposals.
The broader political theory debate between technocratic governance (expert-led decision-making) and democratic populism.
Case studies of institutional strain on central bank legitimacy, such as the Eurozone crisis or the policy responses to the 2008 financial crisis and post-COVID-19 inflation.
11.6K views467likes35:30Original Release: 2025-09-19
from the Road Center for International Economics and Finance at the Watson School at Brown University. My name is Mark Ble. I'm the host of the Road Center podcast. At the end of last semester, I had a chance to talk to Lee Downey. She's a political theorist in London at Kings and she has a book out called Our Money: Monetary Policy as if democracy matters. And we had a good wide-ranging talk about monetary policy, central banks, and the whole shebang. We plan to release that conversation this fall. In the interim, a few things have happened which have, let's say, altered the conversation around central banking in the United States and elsewhere. So, we decided to call Lee back up for a follow-up conversation and kind of incorporate those new things into our old conversation. So, what we've got here is a two-parter. Part one, which you're going to hear this week, is the original conversation. Part two is the update where we basically plug in all the stuff that we've learned since then.
Here's mine and Leia's conversation from last May. This is part one. Hope you enjoy it. Remember and watch part two.
>> Leia, welcome to the pod.
>> Thanks for having me. Excited to be here.
>> So, uh, the first thing I should do is apologize for mispronouncing your name for the first five years that I knew you. So, put listeners in the context of this. Um, Leia, L E Ah, if you're Scottish, would be >> Lee.
>> So, for the first five years I knew Leia, I said Lee.
>> Mhm.
>> And then eventually she said, you know, my name's Leia. and I went, "Oh, >> yeah, >> that was rather awkward." So, putting that to one side, uh, we're here today to talk about this fabulous new book, which is Our Money: Monetary Policy As if Democracy Matters. I mean, the title kind of like says quite a lot, doesn't it? I mean, the as if bit. Did you actually have to did you have to fight to get it in italics?
>> Yeah, actually, I fought a little bit to get it in italics and I fought to get on the back >> the little note about it being legal tender.
>> Ah, right. Right. Okay. Yeah. Which of course could be a counterfeit claim.
>> There you go.
>> There you go. So you watch out for that.
>> All right. So, uh, let's set the stage for this, right? Um, >> central banks.
>> Mhm.
>> Loads of people have written about central banks. They became the sort of like quintessential domestic and international economic governors.
>> Yep.
>> Uh, we delegated pretty much every responsibility we could to them on on the basis of a theory that politicians can't be trusted with money ever. Y >> right. About time inconsistency. And we thought that's good. So then we'll give it to these unelected technocrats, >> right?
>> Uh then came the financial crisis and uh they basically have two tools which is raise and lower the price of borrowing money and buy and sell some assets to influence liquidity conditions. Right.
Yeah.
>> And uh it turned out that wasn't enough to stem the aspects of the crisis even if they stopped the economy falling through the floor. They are also a bit prone to austerity.
>> Mhm.
>> And uh for a while they were held in quite malador. Mhm.
>> Um then along came >> co >> and co we asked them again to deal with inflation rather than deflation which was the policy the last time and they didn't do that bad a job with it.
>> So so yeah two cheers for central banks right but along comes Leia and Leia says hang on a minute >> this is not right because ultimately this isn't just about some kind of technical argument about political business cycles or something like this.
There's deep philosophical questions here as to what we're doing and why we're doing it and that's what you try and explore. So just open this up for us. What what's what's the big picture story here?
>> Yeah, definitely. So uh you're right in that I sort of start from first principles in the book, right? So what does central banks do? Uh well they do lots of things but one of the main things that they do is engage in monetary policy and for me in the book I define monetary policy as the regulation of money creation. Right? So central banks of course create money themselves but they also regulate private money creation that we see happening in in private financial industries. So when you just think of it that way, it's like that's a massive state power, right?
Like when do we create money? On what basis do we create money? How do we create money? Who does it go to? And that has huge implications for how we sort of create and recreate our social world, our political world, our physical world, and that's just politics, right?
So the fact that those two things are thought to be separable is just kind of the just bizarre from a sort of observational perspective. And then essentially what the book does is it does a deep dive into the reasons for and against separating those things, right? And essentially I say the reasons for separating them in central bank independence are not quite as compelling as we might have thought that they were >> and the reasons against it are actually really quite important. So we kind of have things backwards a little bit.
>> So you're a central bank revisionist.
>> Yeah, you could say that.
>> You could say that. Okay. So let's take this one step at a time then. Right.
What is the difference in your mind between fiscal and monetary policy and why is that important?
>> Very good question. Um I guess the sort of mundane answer is that fiscal policy as currently uh constructed right is about sort of tax and spend right and usually happens in the legislature.
Monetary policy is more macro in a sense. It's less about distribution explicitly, although of course it has massive distributional consequences, and more about when how do we steer the economy as a whole, right? How do we speed it up, slow it down, push it in different directions, >> but but you speed things up by giving people a tax cut?
>> Yeah. No, I think that they're like very I think they're fundamentally inextricably linked. Like I think that the division is pretty artificial.
>> So then why does the division exist and who benefits from the division?
>> Well, there we go. So the division exists I think at least at an institutional level right if you go back in the US for instance to the founding of the Fed 1913 the point there was you were really re you're creating an institution in reaction to a crisis so there had been quite a few financial crises leading up to that period that the private financial world was having to deal with itself and that just was becoming infeasible or they didn't want to do it right they wanted help from the government the government wanted more stability in finance there was also a desire from the financial world to have a central bank because what they noticed was that central banks existed in Europe and not only did that prevent things like bank runs, it also enabled the bank to make a lot more money because they didn't have to worry about bank runs and things, the state would take care of it.
So they get to mobilize finance in in a more um profitable way.
>> So the bank was essentially created explicitly, right, to sustain the private the stability and effectiveness of the private financial industry, right? And at the time it was really much more of a public private partnership than it is today. I I mean it was formally constructed as a banker's bank, right? So private banks then and now own the Federal Reserve system in a sort of meaningful sense.
>> Um but as it history pro progresses, it becomes more of a of an sort of an engine of public policy, right? So how are we we're going to actually engage in buying and selling assets in alter in adjusting interest rates in regulation from a public policy perspective but the aim kind of never changes right so we now have an the institution in the United States that is in charge of the regulation of money creation uh from the perspective of the government right public policy uh doing that in order to sustain the stability of the private financial system right >> and like if you think about that from first principles. It's a bit strange.
Historically, it makes sense and I go into that in the book in terms of like why that happened, but just from first principles from a democratic perspective, it's a bit weird.
>> Okay, but spell that out because people might not really think that one through.
Why is that weird? What are these first principles?
>> That's weird because at one might think that in a democratic society, if we think of democracy as a form of government in which citizens collectively steer policy, right? So, they're actually determining the rules that they live by. that it would be strange that you'd have an institution within the government that is ostensibly democratic that is pretty much just securing policy in the interest of a particular sector that is at times explicitly diametrically opposed to the legislature that's meant to be instituting policy from a more traditionally democratic perspective.
>> So if I put my central bank hat on I've got one under here. So I put on my set I go well you know I can understand those democratic concerns but ultimately you know we have transparency in our deliberations and ultimately all the stuff the legislature wants you can't have unless you have monetary stability so therefore you need to let us do our job and then you can do your job right that's what's wrong with that argument >> right so two things are wrong with that argument in my view the first is I just I just agree and in the book the sort of gambit of the book right is that the Fed is actually both democratically legitimate and accountable and yet still a problem for democracy. So what how does that work? Right? So because most people critiquing contemporary central banks say it should be more accountable or it's actually not legitimate and I disagree with that. Like I think it is set up like most of the rest of the administrative state. It's delegated power from the legislature. The legislature decided that itself and it's held accountable like right for its past actions. The problem is that leaves no space for the central bank to guide policy going forward. Right? So my favorite quote from about this is actually from a British case where an MP says to the governor of the Bank of England who's testifying in front of parliament like I'm paraphrasing but essentially like what good is this this sort of accountability where I just ask you a question and you give me a very aerodite explanation like how what what sort of power does that give me as a democratic official. So that's the gap that I think we have, right?
>> Then to the second part of your question, which is, yeah, okay, but maybe we give up on that because price stability is really important.
>> Well, I just don't buy the argument that you can't have price some degree of price stability, right? And quote unquote good monetary policy in a world in which the central bank is like most other administrative agencies, right?
Like why is it special? The argument for it being special, I don't buy. And I think it just gives it more a degree of dominance actually and separation that ultimately that causes the big problem for democracy which is that >> it's not that the legislature needs to be making monetary policy every day but it needs to maintain the sense that it has power over that and could do things differently. So that starts to erode when you've got the central bank doing its own thing for an extended period of time kind of in whatever way and towards whatever ends it wants.
>> Okay. So taking your revisionism seriously here. Um this leads us to a place where you know my central other central bank hat you have too.
>> I've too an even stricter central bank says yeah but you've got a rather naive view of politics haven't you? because ultimately we know they're a bunch of money grubbing careerists who will like throw their grandma under a bus for an extra five bucks. Um they can't be trusted. They're time inconsistent if you want to be fancy about it. And they can't make credible commitments. This is the Ulysy, not Ulyses problem. Adysius, right? Adysius problem. Well, it's true.
I always think No, but the weird thing is when you have Ulyses in your head, I immediately jump to James Joyce.
>> And like the James Joyce central banks story suddenly gets really weird, right?
So let's not do James.
>> Okay, we'll do Odysius.
>> Yes, Ulyses and the Sirens, right? So, so what's what's isn't that the usual thing? They can't be trusted, etc. >> Yes. So, this is the classic story, right? So, Ulisses, Odysius, whoever, right, wanted to listen to the sirens on the boat. And so, in order to avoid the temptation of the siren sound and crashing the boat, he essentially had his crew tie him to the mast of the boat and the crew sailed the ship and he got to hear the whatever the song. And so the analogy goes that the legislature to avoid the temptation of bad policy should tie itself to the mast of central bank independence. Now like we could spend an entire podcast just going through the problems with that analogy in my view. There are many. It's not actually a useful analogy. But just to stick to the like original question of sort of aren't politicians just sort of terrible and very simplistic people and why would we ever give them power especially over money? Well, I just think that that model is way too simple, right? So, think of it. Let's start here. There are obviously policies, tax policies, military policies, environmental policies, immigration policies that would seem very attractive in the short term, right, before an election, right, that would have bad long-term consequences. And yet, we still seem to think and not even demand that those policies are under the power of elected officials, right? Right.
Okay. So, how is that that different to monetary policy in that instance? Right?
So, in the same the the second thing I would say is that it's I think it's pretty unfair to elected officials and voters to suggest that they're really that simple, right? That they don't actually consider long-term consequences, right? So, you know, just all the things I just mentioned, right?
Consider tax policy.
>> Suppose somebody's running for office, they say, "I'm going to eliminate taxes completely, right? Everyone vote for me." Like >> it's actually going on just now. This is no longer a thought experiment.
>> No comment. Yeah, exactly. But so like imagine imagine then what happens, right? First of all, voters some voters don't believe them, right? Other politicians say, "Hey, dude, that's going to have really bad long-term consequences." So like people aren't just idiots, right? Not all of them at least.
>> And so the idea that that model is true, I just don't find very compelling. And the ev more evidence for that is central bank independence. Right? The legislature could eliminate the Fed and juice the markets tomorrow. True.
>> Right. But it doesn't because it has some degree of care for long-term consequences. Right.
>> Right. So I just think the model is a bit too like >> simple. Yeah. Exactly. It's just not a good reflection of reality.
>> So does that solve the problem of trust? I mean we are in a moment whereby you know we're now betting the house on a theory of tariffs which is shared by precisely three people. Um >> can you call that what they share a theory? I I think you can I actually take it more seriously than most in the sense that if you think that uh you know with the demise of uh TTIP and TPP you know basically and then you know the behind Trump's tariffs etc right as as infinite industry protection I mean the free trade consensus died in 2015 and that was and that was right and that was 10 years ago right so well let's take this as an analogy for this then right I mean are you part of a kind of like movement that 10 years from now you want to see the end the central bank independence.
>> Uh yes and no, right? Like like yes.
>> Don't have it both ways. I mean yes or no, right?
>> Well then I guess in a simple sense yes, right? Like okay, so let let me give you the story on this, right? So I think this is this is important to say. One of the core observations in the book which seems pretty obvious but I think has pretty consequential consequences if you can if you if you will is that uh any monetary policy that is constructed as if democracy matters will have to be political >> right just foundationally democracy is a political form of governance so if you want to exert democratic power over monetary policy monetary policy has to be in the political domain >> but of course for something to be political doesn't mean a that it has a particular politics, right? So for it to be political doesn't mean that we need to be using monetary policy to achieve particular partisan ends and second just because mon democratic monetary policy is political doesn't mean all political monetary policy is democratic. Right? So if we have the president running monetary policy on the basis of a whim, >> that is not what I'm arguing for here.
So that would be a form of no more central bank independence, but it's not the form I would want to see. Okay?
Right. And like there are very good reasons for that. Like even just the very obvious constitutional reasons that that makes the president look a lot like a king. There's a reason the president doesn't have powers of the purse and monetary policy is a form of power of the purse. Right. So that's pretty clear. But I would want to see it right like if the legislature were to institute what I suggest that they should in the book that would be the end of central bank independence as we know it today. For sure.
>> All right. So before we get to your final concrete suggestions, let's just work it through by stages again, right?
>> Well, why not just go with more accountability, right? Cuz they used to be, you know, there was nothing. And then basically he started to get the speeches. They were all reducted, right?
And then they did less reduction. And then he started to go for forward guidance, which was basically I'm telling you what I'm going to do, right?
>> Which is of course time inconsistent.
Can be.
>> That's true. Right. Fair fair point actually. Um so you know why not just go with more transparency in the sense or more accountability or different accountability mechanisms because it it seems to me you we still even if politicians are more sophisticated etc right we can have let's say how can I put this the yahoo quotient right the sort of like and you didn't see that one coming but there you go right and surely it's better to have some kind of you know independence in what is an absolutely crucial function for everyone money creation rather than sort of like oh now I just run the printing presses, right?
>> Yeah. Yeah. Yeah. Okay. I want to say two things there. One about the yahoos, yahoos, whatever you want to call them, and the other about accountability. So, the first is that it's important to like really reckon with the fact that democracy is risky like properly construed like democracy is risky particularly for those people who benefit from the status quo because you are opening yourself up. You have for it to be democratic, you genuinely have to open yourself up to being ruled by people you disagree with, right? So like that's like an uncomfortable feeling that we all have to get used to if we actually want a proper democracy.
>> But secondly, I think the yahoo issue is a little bit worse in the US currently because of this sort of delegation.
Right. So >> So that's the that's the problem >> partly. Yeah.
>> Right. Walk me through that one.
>> So when you delegate meaningful power away from the legislature, right? like power like that can actually achieve stuff for people.
>> You incentivize a certain performative style of politics, right? Let's build wall and make Mexico pay for it, right?
Like let's let's have clean air and water for everyone like no child left behind, right? When you're not actually responsible for delivering that and you delegate that power to an administrative agency and say get that done, then you create this kind of performativity in the legislature and it's a vicious cycle, right? Because once the performativity happens, everyone's like, why would we give those crazy people any more power? Cuz they're crazy. And so more power goes to the administrative state, more performativity, more power to the So I actually think there's a cycle here that is making the problem worse.
>> There's another version of that though is if you know if the American one is the sort of like the performative one, what you get with the British one where you currently reside.
>> Yes.
>> Is uh a sort of in a sense it's classically the British version of this.
The American one would be like loud and performative angry and the British one is basically a world in which there's nothing to do because the Bank of England have got this and the fiscal rules have got the fiscal side right and so literally you show up in parliament and you just wait for results.
>> Y >> and that's why you end up doing sort of legislation about nonsense because there's there's nothing for you to do.
So that's hollowing out democracy.
>> Exactly.
>> So that's so okay. So I think I I'm buying more of this >> now. Okay. If that's the case that basically politicians even it's not not that they can be trusted, you should put more power in their hands because that's the essence of democracy. And if you keep taking the power away and giving it to technocrats, then you're undermining democracy which leads to all sorts of complications probably worse than the thing you would solve with the delegation. Right? This is where we are, right? What does your ideal form of independent central bank look like?
>> Yeah. So this is where we come to accountability, right? that you brought up before where a lot of people want more accountability and more transparency which makes sense because they go together, right? So to classic uh theory of accountability, you use transparency to figure out what people did in the past. You then apply the rules that existed at the time and potentially punish them if they violated the rules. Right? So this is what we see with legislators all the time because rather than the courts, usually it's the legislature that holds the central bank to account. You come in front of the legislature, what did you do? Why did you do it? Okay, fine. It was within the mandate or not.
what they don't have and what I my suggestion is is a way for the legislature to regularly know and show its power over the central bank. Right?
So to engage in not this backward-looking accountability mechanism but a forward-looking way of steering policy. Okay? Right? So this is what I call iterative governance. Right?
So it's essentially active management of the legislature or sorry by the legislature of the central bank.
>> So does this mean giving them targets?
Does this mean saying we want credit policy that looks like this?
>> So it could be lots of different things, right? In theory, the ones that I suggest in the book in the context of US monetary policy are regularly rechartering the Federal Reserve. So that would which historically by the way was already the case and which would enable the legislature to sort of steer things going forward at an institutional level. Right? So should reserve banks that are all over the country still actually be owned and pay dividends to private industry right or should they be you know regional investment banks or you know this kind of thing. Should we be paying interest on reserves or should we have you know all of these sorts of questions like institutional questions?
>> Then I also suggest a more like an annual form of credit guidance, right?
Right. And so what this would be is the legislature voting on a the way I cash it out in the book is voting on what I call a preferred asset taxonomy. So you could have a way of scoring assets that are like we like we want more in this region, we want more in this sector, we want fewer here, we blah blah blah, >> but it could be as extensive or limited as they wanted, right? So we essentially they could vote every year and say we want >> no credit policy, but that's what we're saying explicitly to you. Right? Or they could say we want to see more credit allocation in the west of the country and in green energy and you know less in healthcare. I don't know whatever but they they would be taking a stand in an explicit way which would bring home to both citizens and the central bank and the elected officials themselves that they actually do have levers of power over how this works >> and they would be held responsible for the outcomes.
>> Exactly.
But I mean, you know, you live in the UK, so maybe it looks different there because they're all, you know, constrained with their fiscal rules and their targets and everything, right?
Yeah.
>> But here, I mean, I'm just thinking about the past 8 years, right? So, if you have annual credit guidance, let's just shorthand call it that or at least, you know, a threeyear window or whatever it is, right?
>> You do this sort of stuff. So, we're going to set up the IRA, we're going to do all this stuff, and then the new guy comes in >> and then basically dismantles the whole thing.
>> Yep.
>> You're going to get tremendous volatility in this. Mhm.
>> And if this was just a normal country, that would be fine. But it does print the global reserve asset.
>> Yep.
>> And all of these things would be hugely disruptive and the people who are affected by it are truly global, right?
Do you really want to bring that level of volatility into this thing?
>> Yeah. Well, I think it's important to distinguish between what we think about as volatility and what we think about as variation, right? So volatility is generally thought of as sort of unpredictable and undesirable, right? So like you don't see it coming and all of a sudden boom, right?
>> Or just you could know it's coming in the sense that the other guy's going to win the election and what you're going to do is dismantle everything you did for the past three years. So anyone who did investment decisions based upon your guidance is now carrying the wrong end of the bag.
>> Right. Right. Right. But essentially what I argue is that you're always going to get some degree of political volatility or variation in in monetary policy because it like you know take the crisis right when things go down then big time then the government steps in right or somebody is elected who decides I'm going to get involved in this because I can and they do you know so it's always kind of lurking in the background. The question is, does it happen sort of unpredictably and erratically and really dangerously or do you allow for a mechanism that enables political um input into the system at a regular basis that is actually predictable. So the markets see coming kind of like an election where okay, you know, pro this guy's going to get elected, maybe he's going to do some crazy stuff, but we see that kind of coming. Yes. um where so it's it's undoubtable that there would be more variation in the system because it would be more politically inflcted. Right? This is back to the observation that for it to be democratic it's got to be political in a meaningful sense. That means there probably will be more volatility.
>> But you try and do it in a way that is uh sort of predictable and desirable, right? And allows for people to kind of see it coming to interpret it and also to kind of um guide it, right? So, like if if there's a somebody who's coming about to run for office and they're saying they're going to do this and it's going to explode the entire global economy, like well, recent evidence says maybe we vote for them anyway, but like maybe you don't. Maybe someone argues against it, that kind of stuff. So, >> but with the Fed in particular, um it's the global central bank. Nobody wants to talk about this, right?
>> Oh, yeah. Yeah. Yeah.
>> So, in a world of relatively closed economies that make the same stuff and occasionally swap things with each other, right? sort of where where the current incumbents would like to get back to in a sense >> you can have highly accountable in your sense central banking.
>> Yeah.
>> But let me give an example and I'll call this the aditi question and you will understand why right >> um so this is after Aditi Sahazerbudi one of our friends and colleagues who writes on swaps right y so what the fed does is it has these swap networks >> and the swap networks make total sense from the point of view of a global governance problem. So basically for those who don't follow the finer points of this stuff, uh basically more dollars are created outside the United States and inside the United States every year in the form of dollar loans done by people who can't get access to the Fed.
So if those loans end up on the balance sheets of financial firms that don't have dollar access and those loans go bad, they're really really in trouble.
So to and that reverberates back to the US and to everyone else. So to kind of cut those transmission mechanisms, the Fed agrees to swap large amounts of currency. So yens for dollars, pounds for dollars, etc. So that those central banks actually have access to dollars and can affect, you know, bail effectively bail out their banks.
>> Now after 2008, a lot of people went, "Hang on a minute."
>> So we we put taxpayers money uh in the Royal Bank of Scotland group that was run by Fred the Shred. uh we we bailed out the Germans who were running operational leverage of 60 to1 on an average Tuesday. Y um why are we doing this? This is nonsense. Right? So a really democratic monetary policy would actually see these as dreadful risks and externalities and would probably get rid of them which would make the entire system more democratic but a lot more risky. Is that worth it?
>> Yep. Uh from a democratic perspective, yes, it has to be as you say, right?
Like absolutely. So monetary policy as if democracy matters as the book title suggests like would have to be more stringently domestically empowered like for sure right but like but then the question is like okay well then maybe I'm just not democratic because that's just insane right I actually don't think it is that insane right so I think drawing more clear domestic lines around the sort of things like swap lines right the euro dollar market regulation of the euro dollar market etc would actually be in my view a good thing Because one from a democratic perspective because you're getting more Democratic input over that, but two also because like who like do we really think that the system right now is a good one. Like it's the Fed that's deciding who the the thing you left out of the story, right? Is that the Fed decides who gets those swap lines? Not everybody gets them. That's right.
Right. Like some countries are like, "Please can we have dollars? We desperately not need dollars." And JPAL, well, not JPL, but would be in the future would say, "Actually, no. Today I don't really like your country, so I'm not going to do that." So like both wildly undemocratic, but also like totally arbitrary and kind of bizarre. I mean not totally arbitrary because it's done because it's on the basis of going back to the founding of the Fed securing the stability and effectiveness of the financial system, right? The international financial system.
>> So if Deutsche Bank blows up, that's probably your problem as much as it's Germany's problem.
>> Yeah. But like is that is sa is the fed saving Deutsche Bank really the best move like in the long term and especially from a democratic perspective for the global population I'm not so sure. So like I don't know my view is that like it's it's a tricky question in the sense of like what's the alternative right is the alternative like international collapse because nobody does anything as a result that's bad is the alternative that it's that the US exerts more domestic control over monetary policy including things like swap lines and the euro dollar market and as a result there is an international reaction to that which is like oh I guess we can't depend on the international euro dollar anymore and all this massive financial speculation that goes on the back of it. We need to sort something else out that's either more domestically democratic in their own country or there's a new political discussion about international financial governance. But right now it's like all pretty shady and like I I'm not a big fan >> and I'm sympathetic to that in the sense that the sort of the turn to technocracy works so long as you have what I call output legitimacy, right? that basically you say you're the best sausage maker, the sausages are delicious.
>> And then when it all goes wrong and the sausages taste bad, people say, "Who put you in charge in the first place?" And then the whole thing becomes politicized in a different way. But the counter to that is the adults in the room claim, right? That in a time of increasing polarization, media fragmentation, and people believing frankly whatever they want that the world does work in certain ways, people do have certain degrees of expertise. And you know, if you do things like just basically have a tariff war for the sake of it, it probably will be damaging and it probably will not result in the mass reindustrialization of 30 million jobs, right? It's probably, let's be honest, it's not going to work, right? So, if that's the case, don't you want the adults in the room? I mean, in the sense that it's the it's the least bad option because I want to be a Democrat. I want to be a Democrat with you, but I don't want to be a Democrat with these guys.
>> No, no, no. But like the argument that I'm making is not that we don't want the like adults in the room or that we don't want to use the best sausage maker to make our sausages. Right? The whole claim is that what we want is to employ expertise in a democracy but not be ruled by experts. Right? So how do you create a system in which the legislature is still maintains a certain degree of effective power over the expert? Right?
So like I want you to think about you know more investment in North Carolina and less in California. but also recognizes that like they don't have the expertise. So like they're employing that expertise and showing them sort of here are some options, here are hows we can do that, here's how we can do that.
So you still have the adult in the room.
It's just that the sausage m maker isn't in charge, right? They're they're responding to a different degree of like >> you're telling them whether you're making Italian sausage or not.
>> Yes. Right. Yes. Yes. And like as a like not only is that I think more democratic but it also interestingly would allow for a different relationship between the legislature and the expert that could actually enable the discretion of expertise. Right? So, so, so like if if the expert is not obsessed with adhering to a mandate because that's the sort of legal technical way in which they're like, you know, legitimate, but instead is engaged in like an active management relationship, right? Then you get a lot more sort of creativity and you could get better kind of policy outcomes, right? So, I think about this with like um you know, think of any management relationship like a manager and their employee, right? Instead of saying like I'm writing out four things for you to do, it's like we'll check in. We'll see how it's going. You tell me what's working, what's not working, that kind of thing, right?
>> So, it's not that I want to like rid the world of technocrats and experts. Like, I love the administrative state. I want to build it in a way that's actually sustainable and empowers democracies over time.
Doesn't become a target of the democracy. Right.
>> Exactly. Exactly. And I'm particularly struck by your idea that ultimately by not letting them hide behind fiscal rules, not letting them hide behind, oh, the central banks got that, you kind of you reprofessionalize politics. You say you have to be serious people.
>> Exactly. It's like we're you you this is your power and therefore you have to like deal with it. And so I think both you're rep-professionalizing them. You have to be serious people and you're going to attract like politics is not a very attractive business for a lot of very intelligent curious like ambitious kids these days like my students I don't know about yours are not very interested in politics like >> and that is I think a part of virtue of the fact that we just like have completely sucked it dry of like actually being able to do something. I mean, it's no wonder people are voting for parties all over the world that are saying, "Let's blow it up, like, you know, drain the swamp, take back control." Because it's true in a sense that politicians have delegated away so much power that like it doesn't really matter who's in that seat. And that is not a good state for democracy if it doesn't matter who's in that seat.
>> Exactly.
>> Is there anything else that we haven't covered?
>> Oh boy. Um, I think it's just worth maybe like emphasizing at the end too that this whole point about like democracy and it being risky and like embracing that like it's a tricky thing to argue especially at this moment in time. But I think one analogy that I use at the end of the book that I f I found useful was like was suffrage, right? So at the time when women were arguing for the vote, one of the major arguments against was that's just going to produce bad policy, right?
like we can't let women vote, that'll have bad that'll produce bad policy. But it was obviously the democratic thing to do to extend the vote to women. And in the end, obviously, that wasn't the case that like women voting produce bad policy. But it also was just you have to take >> the conclusions of the argument if you're really going to if you're really going to commit to it, right? So, if you want to sit there and tell me that like actually I care more about the stability of the international financial system than I do about democracy, then like okay, fine. That's your prerogative. But like if you're going to say that you are committed to democracy then like this is the conclusion. Yeah. You know and like we have to have that conversation in the country. Uh and I don't think we have yet.
>> You might have wanted to call the book the democratic risk.
>> Oh I like that >> because that's ultimately the essence of what you've got to take the democratic risk.
>> Yeah.
>> All right. Maybe that can be the title for your next one.
>> There you go. Next one. Yeah. I'm on it.
Well, Leia Downey, thank you very much for coming in and being on the podcast.
>> Thanks for having me. It's been a lot of fun.
Up Next
11:30
Fiscal Dominance and the Fed's Waning Influence: Gold's New Role
@2DollarsInvesting
13.3K views•2025-08-14
5:07
Impact of Yuan in Indo-Russian Trade Amid Sanctions
@WION
261.9K views•2022-07-01
10:33
Behavioral Economics Explained: Rationality, Nudges, and Risk
@crashcourse
1.1M views•2016-03-12

113:18
The Age of Easy Money: Fed & Inflation | Full Documentary
@frontline
21.2M views•2023-03-15
Related Study Plans & Knowledge Roadmaps
Structured learning paths in Economics
economics
Sovereign Debt: Defaults, IMF & Restructuring
01Introduction to Sovereign Debt & Government Bonds
02Debt Sustainability & Credit Ratings
03Anatomy and History of Debt Crises
+ 2 more learning modules
12h5 modules
Explore Roadmap
economics
Market Design: Matching Theory & Gale-Shapley
01Introduction to Market Design and Price-Free Markets
02Two-Sided Matching & The Gale-Shapley Algorithm
03School Choice Systems and Mechanism Design
+ 2 more learning modules
10h5 modules
Explore Roadmap
economics
Impossible Trinity: Forex, Capital & Policy
01Introduction to Monetary Policy and Central Banking
02Exchange Rates and International Capital Flows
03The Mundell-Fleming Model
+ 2 more learning modules
8h5 modules
Explore Roadmap
economics
Healthcare Economics: Market Failures & Systems
01Introduction to Healthcare Markets and Market Failure
02Asymmetric Information and Adverse Selection
03Moral Hazard and Insurance Design
+ 2 more learning modules
12h5 modules
Explore Roadmap