











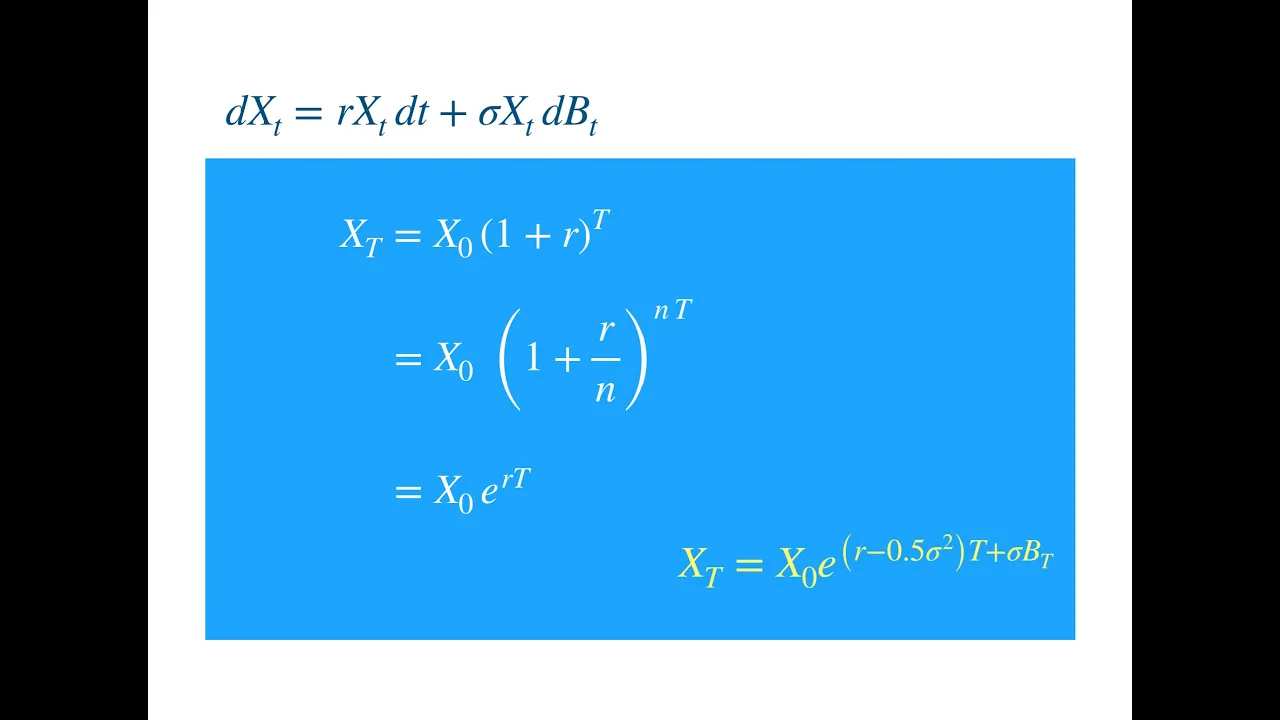


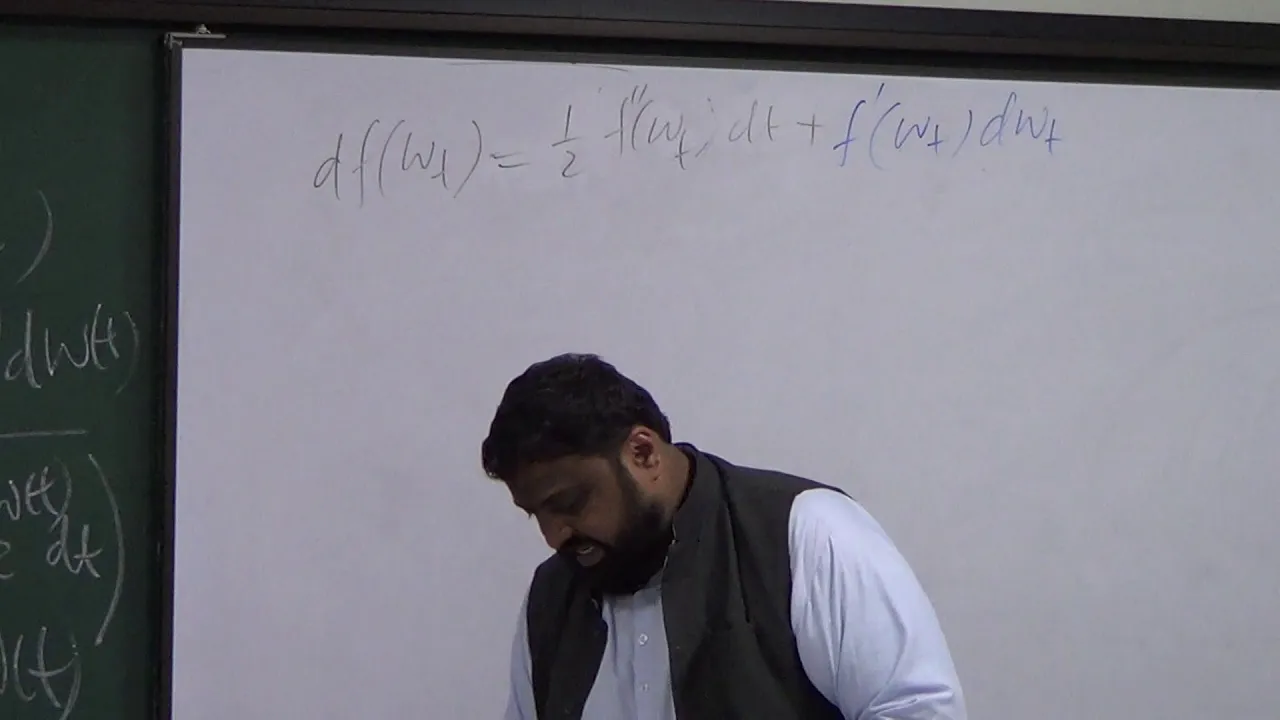



The Ito integral for simple adapted processes is defined as the sum of the process values at left endpoints multiplied by Brownian motion increments, and it forms a martingale with respect to the filtration of the Brownian motion, meaning its expected value given past information equals its current value.
Stochastic Calculus: Ito Integral Definition & Properties
Added:Foundational Probability Theory and Measure Theory, including sigma-algebras, probability spaces, and conditional expectation.
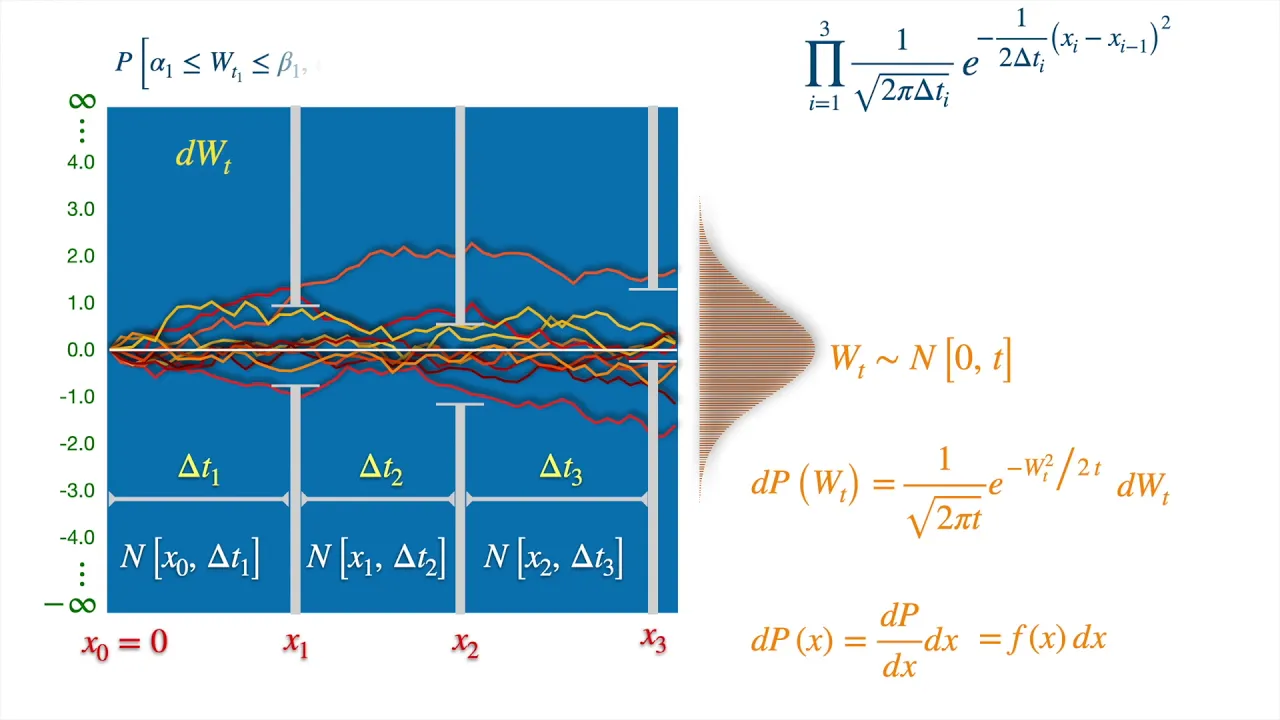
Definition and properties of Brownian Motion (Wiener Process), particularly its continuous but non-differentiable paths and quadratic variation.
The concepts of filtration, adapted stochastic processes, and martingales in continuous time.
Classical Riemann-Stieltjes integration, specifically understanding why it cannot be applied directly to integrators with unbounded variation.
Ito's Lemma, which acts as the stochastic counterpart to the classical chain rule in calculus.
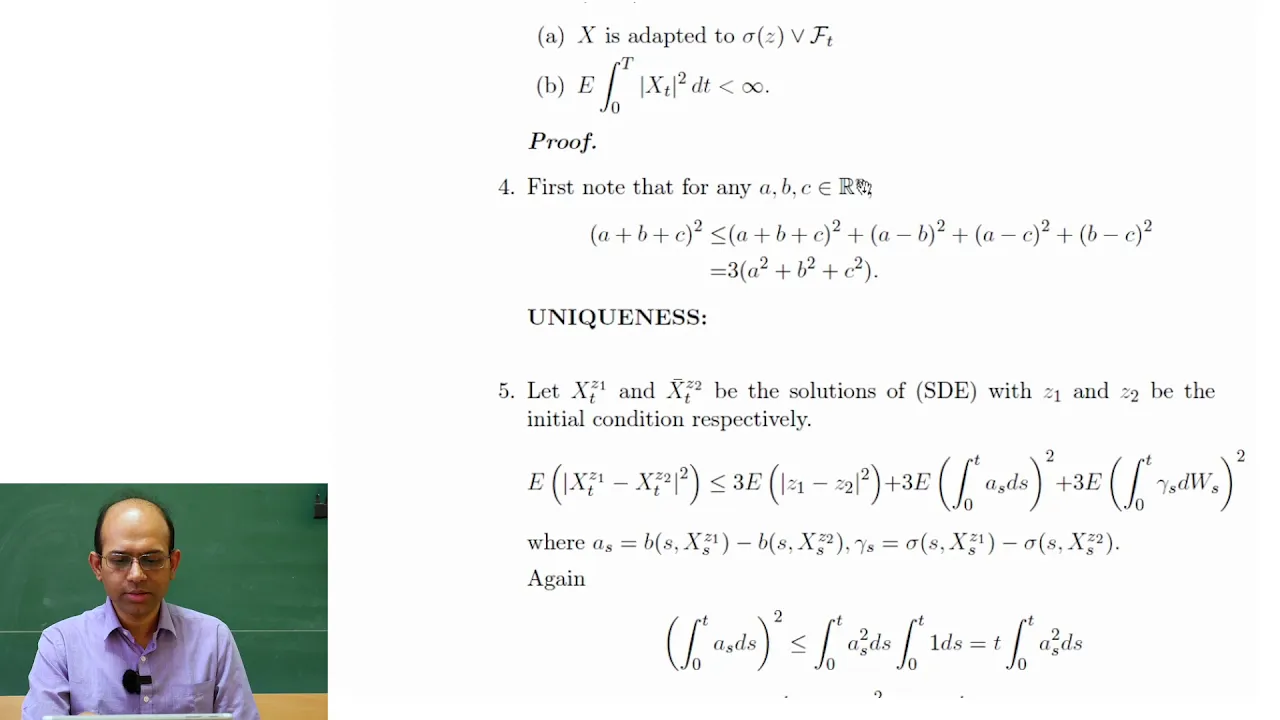
Stochastic Differential Equations (SDEs), including existence and uniqueness theorems and analytical solutions for models like Geometric Brownian Motion.
Girsanov's Theorem and the concept of change of probability measure, which are essential for risk-neutral valuation.
The Stratonovich Integral, exploring how it differs from the Ito Integral and when each framework is preferred.
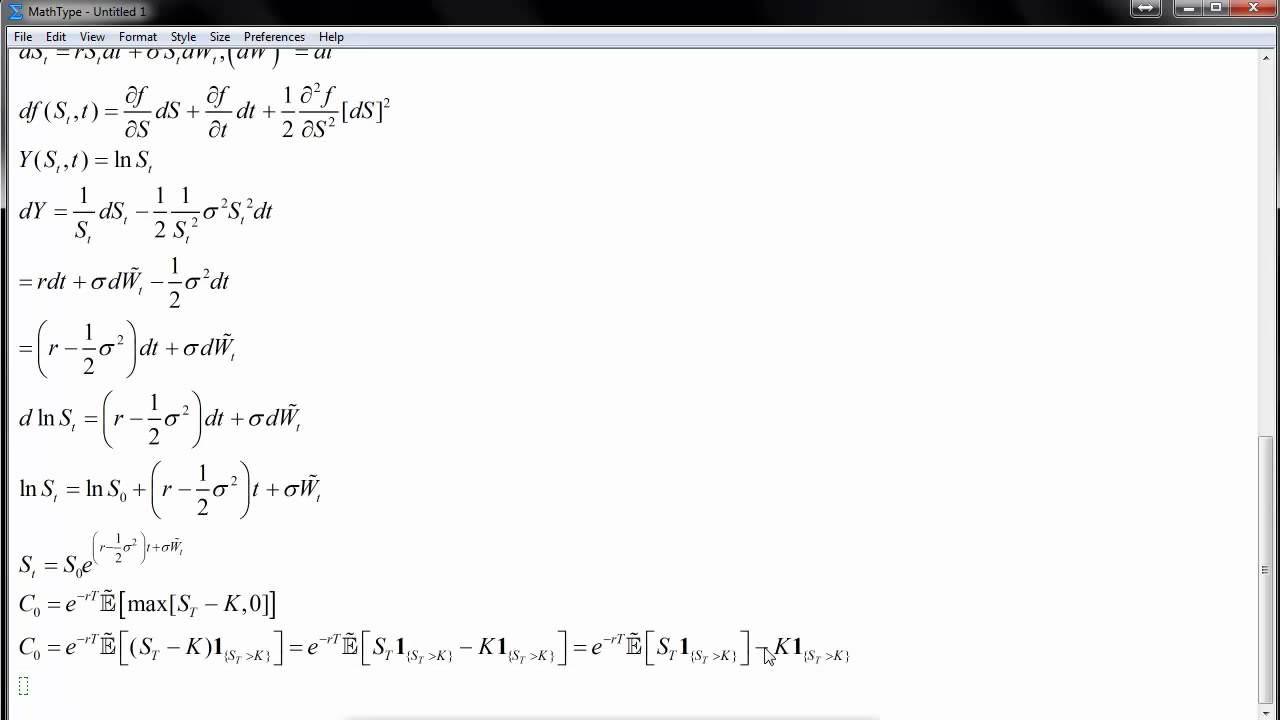
Applications in Quantitative Finance, such as option pricing using the Black-Scholes-Merton framework.
209 views2likes52:32Original Release: 2021-05-14
dear students welcome back to the video lectures and we have reached chapter four in which we will deal with stochastic calculus and in particular we will discuss sections 4.1 and 4.2 in this video lecture and there we will introduce a stochastic integration yeah and the aim is to come up with the general definition of a stochastic integral the general setup here is as follows we are given the brownian motion wt t greater equal to zero and a filtration script f t t greater equal to zero and now we would like to make sense of the following stochastic integral so we would like to define following stochastic integral the integral from 0 to capital t of delta t d wt where capital t here is something like the end time of a financial contract so we will look at a term delta t d wt over the lifetime of a financial contract so in fact we are integrating with respect to brownian motion here you see the dwt which is new and delta t the term in front of dwt that is a stochastic process at t greater equal to zero a stochastic process which is adapted to the filtration skipped f of t of the brownian motion well this is new for us right we have not yet seen this before so we need to properly define this and why looking at such a term well in financial mathematics such an integral over the time an integral of delta t dwt that can be seen as the total gain of a financial portfolio now this is a bit premature because we have not even discussed the portfolio yet and but we just want to make to explain you that it actually makes sense to look at this in in quite some detail yeah now as we did with the riemann integrals and with the back integrals for the definition we start with simple processes and these were the piecewise constants that we have seen before before we worked with simple functions but now we'll work with the whole family and therefore we will work with simple processes so let's first define these simple processes so we will use for delta t simple processes and the definition is as follows it's a specially adapted process delta t t greater equal to zero adapted to the filtration uh script f t t greater equal to zero of the brownian motion on the closed interval from zero to capital t it is called simple if there exists a partition of the interval and partition as follows so zero is equal to less or equal to to t0 it's less than t1 less than t2 up to tn which represents the end time capital t of the interval 0 t so we have a partition there exists a partition such that the delta t with an event little omega in omega is equal to the sum of i runs from 0 to n minus 1 of delta ti at an event omega times the indicator function which is then 1 between t i and t i plus one and zero elsewhere so this sum is a simple function so we are in the following setting so we have our this is a straight line a time interval and we have here we have t1 t2 t3 etc up to tn which is equal to capital t here is our zero and then here we have delta t i and that is a randomly a random based on a random event so it can be like this etc right um so every time our event changes our piecewise constants will change that is part of this construction of simple processes all right so that is that is how this is so delta t is a constant on the interval t i t i plus 1 and it has the value at the left point of the interval delta t i and then it's multiplied by this indicator function and therefore we get these these piecewise constant properties yeah so um now let's define the ito integral so if delta t t greater equal to zero is a simple process with an underlying partition from 0 to capital t again t 0 equal to 0 in this case less than t 1 less than t 2 up to t n minus 1 being less than t n which is the final time capital t then we define the ito integral the ito integral which is the object of study in this section as follows for t cap small t in the interval 0 to t we find we look for a k an index k such that our t lies in the interval between t k and t k plus one so we have our timeline again our timeline this is our t zero equal to zero t1 and t2 etc and then we have somewhere in the end we have tn which is equal to t and here we have an interval t k t k plus 1 and in this interval we have our t and this is the setting that we are in all right and then we define the integral we call it capital i i t it's defined as the sum i runs from zero to k minus one of the symbol function delta t i times the winner increment and we had the d w in in the definition w t i plus 1 minus w t i so these are the first k minus 1 elements and then the last element the last element runs in this small piece here this small piece and that is delta t k again we choose the left side point times the increment that is remaining wt minus wtk right so we have the first sum represents the integra the integral up to tk and the final part here the final part here that is this represented by this small element here yes i would like to stress that this integral it is a random variable and so that is also the reason why we wrote this omega here it is a random variable yes so that is an important part now if we take this partition smaller and smaller and so the the the we increase the number of points and the the interval in the partition gets smaller and smaller this can be seen as veena increments these are increments and this is the value so we will be able to define this as the integral from zero to small t of delta u d w u and so that is the definition of the ito integral again as mentioned the ito integral is a random variable it's a process so you have to read it with the omegas here yeah omega omega omega right now let's investigate the properties of this integral i t for the simple adapted processes so the first thing i notice without doing any work let me go back to the definition the first thing i notice is here are increments winner increments they are multiplied by a constant this is a sum uh these these pieces can be small and they are continuous so the first thing we can notice without too much work is that these are continuous parts so the ito integral is made of delta ti these are constants it's made out of the increments and the w has continuous parts so we see quite clearly that i t has continuous parts so since brownian motion has continuous paths the same holds for i t alright second important property is that it is in fact the martingale so in order remember that in order to uh to have something to be a martingale we need to show essentially two properties it should be adapted to the filtration and we have the conditional expectation property well being adapted is quite clear if we go back to the definition here we see that if you look at the time interval you'll see that up we are up to time t and everything up to time t is related to time point t k yeah and the filtration is an increasing filtration and all the terms that are appearing here in this first part all the terms that are appearing here they are concerned with tk's that are less or equal to t and the last term here this last term that has the t so every term in this expression is ft measurable and thus we have adaptiveness adaptedness right so again let's look at that second property had the theorem that we just mentioned that the ito integral i t where small t runs from zero to capital t is in fact a martingale with respect to the filtration skipped f t where t runs from zero to capital t of the brownian motion w t t greater equal to zero and we have just seen that the first part of the proof is easy it's easy to see that i t from the definition of i t is ft measurable and therefore i t where small t runs from 0 to capital t is adapted each term in the definition of it is in fact ft measurable now the second property is that conditional expectation i just mentioned and you you know at the expected value of i t given uh the filtration up to time s should be equal to is and this con conditional expectation to hold is the second fundamental property of the of the martingale for that of course we need to [Music] look at our timeline and we have an s less than small t small t being less or equal to capital t and small s being greater or equal to zero now in order to investigate this we look at our timeline this is again a straight line and we have our time partition here now we look for two indices an index l such in such a way that our time s lies between t l and tl plus one so in this interval and an index k such that our time point small t lies in the interval between t k and t k plus one yes so we look for two of these indices so that this is satisfied s is in tl to tl plus one and small t is in tk to tk plus one now let's rewrite the expression having this in mind so i t is then written as a sum i runs from 0 to l minus 1 first so we take first take the part up to l minus 1 of delta t i again the left point value of the simple process times the linear increment so the brown the increment of brownian motion w t i plus 1 minus wti and then we reach point l and there we have delta t l times the brownian increment w t l plus one minus w t l and then we continue we go from with our index from l plus one to k minus one again we take the left point value for the simple process delta t i times the brownian increment w t i plus 1 minus w t i plus the last part i t is of course an integral running two times small t and small t was in the interval between t k and t k plus 1 so here we have our final term delta t k times w t minus w t k all right so let's look again what uh what this is so we we have the conditional expectation of this expression in fact yeah under the filtration fs now let's look in detail what we get so first of all we we have this conditional expectation so splitting this sum into four terms this is term one this is term two this is term three this is term four and these are exactly the the the sums from the previous page so this is until l minus one this is that specific part between tl plus one and tl this is the part from l plus one to k minus 1 and this is the last part so we have four parts and we look at these four parts individually yeah so we we can tell what happens with each part well let's look at the first part and let's look at the first part well we know that all these points up to tl all these points are earlier than time point s right that is from the definition and so my my filtration is an increasing filtration every term in the first part here is measurable with respect to fl and because we have an increasing filtration so this first part is fl measurable again let's look at the first term i rewrote it here i repeated it here this is fs measurable in fact all these time points are prior to time s and because they are f especially we can use take out what you know so the the expected value of something which has happened in the past is in fact the value itself right so this expectation of the sum i runs from zero to l minus one of delta t i times this brownian increment given the filtration f s is in fact the sum i runs from zero to l minus one delta t i w t i plus one minus w t i and that's it yeah this part is easy it is f s measurable so i can take out what i know and the conditional expectation is just the value because w is a martingale now the second term let's look what we have here in the second term let's look back one slide the second term we have one part here delta tl wtl which is f s measurable because t l is earlier than time s and we have this other part delta t l w t l plus one that requires some extra care let's look at them in detail so we have this expectation to deal with and as i mentioned this this part delta tl wtl that is in fact fs measurable because tl is less or equal to s and wtl is fs measurable so therefore take out what you know you can we can say and this part is also this part is f as measurable take out what you know so rewriting this conditional expectation boils down to delta t l times the expected value of w t l plus one under the filtration f s minus that other part is f as measurable so we can just rewrite this without the expectation minus delta tl wtl now we know that w is a martingale so the expected value of w t l plus 1 the conditional expectation with the filtration f s is in fact ws yeah by the definition of w being a martingale so in the end that is delta tl times ws minus the other part delta tl w tl so in total the result from the second part is delta tl ws minus wtl and from the first part this was remaining now if we look again at these two parts the sum i runs from zero to l minus one of this term plus this term in fact if we combine the two if we combine the two we see that in fact we already have gained we have obtained what we would like yeah so this is in fact this is already is yeah if we would write down is the combination of term one and term two will give us is will give us what we want the conditions for i t being a martingale so the sum of the answers we got from terms 1 and 2 is already the thing that we would like to have but we still have these terms 3 and 4 here term 3 and term 4. so the conclusion is that these terms 3 and 4 they should be equal 0 right they should both be equal zero well let's look again at part three in part three we have the following okay so um well again let's start with this slide so the sum of the first and second terms is already equal to is and that is the answer that we seek to achieve so we need to show that the third and fourth terms are both equal to zero and for that we use a special a special technique double conditional or iterated expectations so let's see where we are and we are in a setting now that we have this is my straight timeline again this is my tl this is my t l plus one here is my s and then here we have t k and here we have t k plus one here we have our t and we are basically concerned now with this range and in the fourth term also with this small range so these two we need to assess now and we use that with double conditioning so the third term the expected value when i runs from l plus one to k minus one um of delta t i times w t i plus 1 minus w t i f s okay so conditional on fs well the brownian increment part is independent of fs remember this remember this from our earlier derivations the brownian increment part is independent of fs and the delta term here the delta term is fti measurable right so we see that this will go in the good direction and we will formally do this with double conditioning so what i'm going to do is i'm going to condition on the i term on wti i can do this because fs is contained in fti yeah so this is uh the expectation is linear so summation can be taken out yeah so what i do here is um you know the summation can be taken out so i look in detail at one of these terms i look in detail at the expected value of delta t i times this brownian increment w t i plus 1 minus t i conditional expectation on the information up to time s so how i do that i do that by this iterated expectations the double expectation i take the expectation and inner expectation with respect to fti so it's the expectation of the expected value of w t i times w t i plus 1 minus wti conditioned on f t i and the outer x expectation remains conditional on fs yeah so this is an example of iterated conditioning and this technique is used quite often now once i do this then this term here becomes well the delta ti term becomes fti measurable and i can get it out of the inner expectation right so i can get it out of the inner expectation you see it here delta t i is out of the inner expectation and then i get this term here which is independent of the filtration fti yes so the this remaining part is independent of fti so the conditional expectation is a regular expectation as we have seen an earlier time and that is equal to zero yeah so a regular expectation of this brownian increment is equal to zero and we can also write it like this this can be seen as as this term minus this term and in fact that is equal this term is wti so we remember head this is a martingale so this is wti so delta t i wti minus delta t i wti is in fact equal to zero so the third term is equal to zero which is good now let's look at the fourth term the fourth term is that that final part right so we were in this setting straight line again and we are at tk t k plus 1 and we look at this and here is t we look at this little piece and f our time point s is somewhere here so let's look at this fourth term and in fact that goes pretty similarly as before yeah the first part is again f this first part is again f t k measurable and therefore when i use double conditioning again the same as we did for a third term we can handle this term in a very similar way so again ftk is ffs is contained in ftk so we can do this double conditioning and the inner the inner expectation we can look in detail this is the expected value of delta tk times the brownian increment wt minus wtk conditioned on the knowledge at time t k and then the outer conditioning is conditional on the knowledge at fs now this part again is ftk measurable and this part is in fact independent of ftk so we repeat the same trick as we did before we take out of the inner expectation delta t k and we write this down as w the conditional expectation of wt conditional on the knowledge up to time t k minus the the measurable thing delta t k w t k this is a martingale and then with this knowledge level this will be equal to w t k w t k and then if we look at it delta t k w t k minus delta t k w t k is indeed zero so also our fourth term is equal to zero and because the first two terms already gave us the desired result we can conclude indeed that the conditional expectation of i t given skipped f s at time s is indeed i of s so the second condition for i t being a martingale also holds true so we can conclude that i t the integral the stochastic integral is a martingale we have a remark here since i t t greater equal to zero is a martingale where the deltas are the simple processes of course then for all t t greater equal to zero we have that the expected value of i t is indeed the expectation of i and zero and that is an integral from zero to zero so that is nothing but zero so we see that the expected value of i t is zero is equal to zero and that implies of course if we look at the variance the variance of i t the variance being equal to the second moment the expected value of i squared t minus the expected value square and this second part here as we see from here that is equal to zero that the variance is nothing but the second moment the expectation of i squared of t yeah so we would like to evaluate this right hand side we would like to look in detail at this and that gives us in fact a very interesting property that gives us the so-called ito isometry so we have the following theorem to evaluate this okay the theorem is called ito isometry for simple processes and there it's given the following the expected value of i squared at some final time t is in fact the expectation of the integral from 0 to capital t of delta square d u and this is this is interesting because this integral here is a riemann integral yeah so delta u is piecewise constant so the riemann integral here is in fact the riemann sum so it is the sum i runs from 0 to n minus 1 of delta square ti so this is the simple function so the square value times the the time interval delta t i plus 1 minus delta t i so that is interesting because this is easily manageable right dw term has disappeared if you wish now if we denote i t as the integral from zero to small t delta u d w u if we denote our stochastic integral as follows our ito integral as follows then this ito isometry tells us that in fact this integral square the expected value of this integral square delta u d w u square right that is in fact the integral of the expected value of the integral of the terms inside the integral square delta square and recall that dw dw was equal to w in in the shorthand notation so recall the shorthand notation dwu dwu is equal to dw so we can take the square inside the integration operator so we can bring the square inside and we use the rule d w u d w u is in fact the u now how to prove this well again we do it pretty much the same way as we did before yeah so we have a time inter vol we have a time partition t0 is equal to zero is less than t1 less than t2 etc up to tn which is the end point of our time interval capital t let this be a partition t zero till t n let that be a partition associated with a simple process and the simple process is again delta t where small t runs from zero to capital t now we have a small t in this interval from zero to capital t small t and let again our index k be such that this t value lies in the interval from t k to t k plus 1. we have an open interval at this side now again we rewrite we write the out we write out i t and we write it as follows it we first go until time point t k so it's a sum i runs from 0 to k minus 1 delta t i again the left point value times the brownian increment w t i plus 1 minus w i and then we have that last term again remember t is in that interval so the last term we have is again the left point rule delta t k times w t minus w t k and now in order to to handle this we use a short form notation we will use d sub i for and it is this term here it is w t i plus 1 minus w t i when i is between 0 and k minus 1 yeah this part and it is defined as wt minus wtk so it's defined as this part when i is equal to k yeah and and in that case we can take this as one sum in fact and so a one sum sum i runs from zero to k of delta ti times di and di has these two definitions and so d i is a little different when i is equal to k and now please notice that w t i plus 1 minus w t i in fact that increment is independent of skipped f t y t i yes and this last part w t minus w t k that is independent of f t so we can benefit from these properties all right let's work it out let's continue with our evaluation and we have to look at uh i square okay and i square i use this notation like in the book and it is nothing but this of course right i t square yeah it's i t square and then we well we have to square we go back one page we have to square this yeah we have to square this and this goes as follows of course this is first of all it is the term squared i runs from 0 to k of delta squared and t i times d i squared but it also has the mixed terms right so we have all these terms here and if we square this sum we have the mixed terms two times delta t i delta t j d i d j and we can write that as follows plus two times the sum where i is less than j and i and j are between zero and k times delta t i delta t j d i d j so this combination here written it up like this this is in fact the writing for i t square please check it yourself now what we are looking at what we are looking for is the expected value of i t square so we look for the expectation of this whole thing so the expected value of this term here and the expectation is a linear operator as you know so we can take we can take the sum out of this and we can bring the expectation inside right and moreover it is again it is a linear operator so we can bring the expectation inside the first term and we can add up the sum where also the expectation is inside the second term so this is just the property of the expectation now if we look at it in detail we first focus on this second term because that is relatively easy yeah we focus on the second term and we have i is less than j so in this definition i is less than j and that means that delta t i times delta t j times d i that is in fact f t j measurable so this part here the first three terms here they are in fact ftj measurable and this last part dj which is by definition wtj plus 1 minus wtj well you know that that part is independent of ftj so we split this uh composition of four terms into two essentially in a part which is ftj measurable and a part which is independent of ftj well while doing that we we can easily evaluate this so um notice that delta t j delta t i d d i n d j are independent random variables and that gives us that the expected value of this is the expected value of the first one the three terms here times the expected value of dj and that is equal to zero because we know that this expected value is equal to zero that is a linear increment so that part is equal to zero now we focus on the first term the first term is the expected value of i t square now and that is equal to the sum i runs from 0 to k of the expected value of delta square t i times d i squared now if we consider this this part again and we look carefully we have of course that delta square ti is fti measurable it is a constant squared it's ft measurable it runs up to ti while di itself is independent of fti and that remember that i is an increment that is independent of f t i and the same holds true for d i squared so again we can look at these these terms and we can see that um we have a term which is ft measurable and a term which is independent of ft so in total the expected value of d of delta square ti times d i squared is in fact the the sum of the x of the product of the expectations expected value of d t i squared times the expected value of d i squared and i runs from 0 to k minus 1.
now note again if we look at this second term here an expected value of d i squared that is the expected value of w t i plus 1 minus w t i square when i runs from 0 to k minus 1 and it is nothing but the expectation of w t minus w t k squared when i is equal to k and we know these expressions we have seen these expressions before the expected value of this square difference is t i plus 1 minus t i when we are in this index set i between 0 and k minus 1 and it is t minus tk when we are at the last index so we know these expressions and we can use them so indeed you see that step by step we have taken everything inside the expectation so we indeed can benefit from the fact that we know this expression and that we can replace it by t i plus 1 minus t i and this expression here we can replace by t minus tk so summarizing summarizing the um the second moment the expected value of i squared is the sum i runs from 0 to k minus 1 of these terms of the expected value of delta square t i times this increment t i plus 1 minus t i which we have just seen plus the last term the expected value of delta square at t k times this increment t minus t k and these sums are hiemann sums expected values they are constant basically the expectations here so these are riemann sums delta squared t is constant on t i to t i plus 1 and therefore we can rewrite this expression as we can take the expectation out and take the sum in because the expectation is of course a linear operator so this this is the expected value of the sum i runs from 0 to k minus 1 of delta square ti times this time increment plus the last term delta square and tk times t minus tk and we can make this finer and finer the more and more points in the partition with distance the mesh smaller and smaller so in fact we can write this riemann sum as a riemann integral it's an expected value of the sum i runs from 0 to k minus 1 of an integral of such a com such a piece remember that this is constant on this so this is identical it's the integral from t i to from t i to t i plus 1 delta square u d u plus that last one the integral from t k to t delta square u d u and if we combine this all and we we see the riemann sum as an integral that is nothing but the expected value of the integral from zero to small t delta square u d u and that is exactly what we were looking for right so that expression is indeed the same as this one here that concludes the proof and today we conclude with some informal notation what have we seen well we have seen before already the informal notation dw dw is equal to dt right and that gave us or that that originated from the quadratic variation the quadratic variation of w in square brackets w wt is equal to t now we have looked at this stochastic integral i t which was the integral from zero to small t delta u d w u that is the integral form with it for a simple process delta and we can write this in differential form as follows d i t is then delta t d w t that is what we can use and this is handy notation because we can also compute calculate with this notation right because if we have d i t d i t then we can simply take delta square t d w t d w t and d w t d w t recall that is d t so we can substitute that so we see that d i t d i t is in fact can be written as delta square t dt and that is the ito isometry that we are using here and it is related to quadratic variation again so we can say the quadratic variation of i so in square brackets i t is the integral of from zero to small t of delta square udu and this tells us that the ito integral accumulates quadratic variation of delta square t per unit time so the quadratic variation of the ito integral is equal to delta square ti t i plus 1 minus t i and in fact that is similar to the notation for brownian motion where the quadratic variation was written like this w the in square bracket w w from 0 to t that was equal to t and that gave us dwt dwt is equal to dt so here we see a similarity for the stochastic integral we have an integral form we have a differential form and we can compute with it we can calculate well this concludes the first lecture for today i thank you for your attention the claim the claim that in fact uh the square the quadratic variation of i t is can be written like this the claim will be in the lecture notes in the slides so i will not discuss them in detail but it will be in the slides it is a rather simple proof so therefore you can do it yourself but my time is up for now so i thank you for your attention
Up Next

37:39
Ito's Lemma in Financial Mathematics: Derivation & Applications
@profbillbyrne
141.6K views•2011-11-15

8:17
JEE Maths | Circles: Pole & Polar Explained with Equations
@TargetPublications
14.4K views•2019-02-23

10:44
Fourier Series Introduction: The Big Idea Explained
@DrTrefor
387K views•2021-05-03

6:00
The Mathematical Impossibility of Accurate World Maps
@Vox
23.3M views•2016-12-02
Related Study Plans & Knowledge Roadmaps
Structured learning paths in Mathematics
mathematics
Projective Geometry: Coordinates & Conics
01From Euclidean to Projective Space
02Homogeneous Coordinates
03Duality and Projective Transformations
+ 2 more learning modules
14h5 modules
Explore Roadmap
mathematics
Tensor Calculus: Vectors to Riemann Curvature
01Mathematical Foundations: Linear Algebra & Calculus
02Covectors, Dual Spaces, and Tensor Basics
03The Metric Tensor and Index Gymnastics
+ 2 more learning modules
40h5 modules
Explore Roadmap
mathematics
Gödel's Incompleteness: Logic, Proofs & Limits
01Introduction to Formal Systems & Hilbert's Dream
02Set Theory, Cardinality, and Cantor's Diagonal Argument
03Arithmetization and Gödel Numbering
+ 2 more learning modules
14h5 modules
Explore Roadmap
mathematics
Galois Theory: Fields, Groups & Solvability
01Foundations of Abstract Algebra: Groups & Fields
02Polynomials & Field Extensions
03Splitting Fields & Symmetries
+ 2 more learning modules
24h5 modules
Explore Roadmap